Download the Complete Report Here
 Enhanced Group, Inc. (ENHA)
DEAG Acquisition Transforms Growth and Earnings Profile; Live Enhanced Gains Traction as Games Costs Normalize
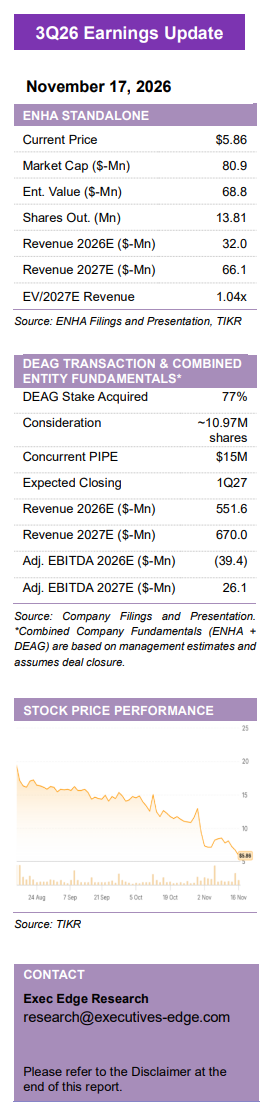
- The proposed DEAG acquisition transforms ENHA into a diversified sports and live entertainment platform, expanding its audience reach, distribution capabilities and acquisition-led growth opportunities. The transaction would add a 77% controlling interest in DEAG, which stages approximately 6,000 events annually and sells over 12 million tickets. Its established touring, festivals and proprietary ticketing operations extend ENHA’s original audience-to-consumer monetization strategy while providing a platform for further industry consolidation. Closing is targeted for 1Q27.
- DEAG introduces an established earnings engine, materially accelerating ENHA’s transition toward consolidated profitability. Management expects combined revenue to increase 21.5% to $670 million in 2027, while adjusted EBITDA improves by $65.5 million to $26.1 million from a $39.4 million loss in 2026. DEAG’s adjusted EBITDA is projected to nearly double from $13.6 million in 2026 to $26.5 million in 2027, supported by higher-margin ticketing and spoken word operations, while ENHA’s existing businesses are expected to deliver a $52.6 million EBITDA improvement through stronger consumer monetization and lower Games costs.
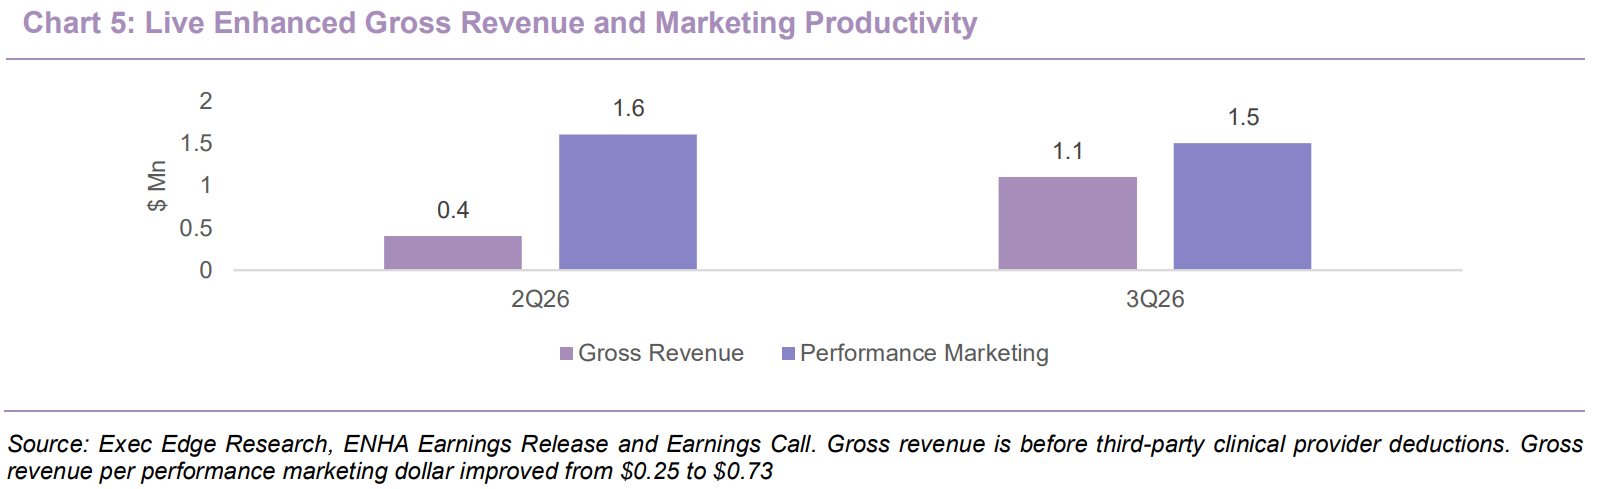
- Live Enhanced’s early commercialization provides encouraging evidence of ENHA’s consumer monetization potential, with improving marketing efficiency creating a foundation for renewed growth. Gross revenue increased 175% sequentially to $1.1 million in 3Q26, while marketing expenditure remained broadly flat at $1.5 million, lifting revenue per marketing dollar from $0.25 to $0.73. Enhanced OS, launched in beta in November, combines proprietary athlete data and personalized protocols, with broader January 2027 commercialization and a planned $199 annual membership supporting recurring engagement and monetization.
- ENHA is repositioning Enhanced Games around repeatable event economics, while the post-inaugural cost reset highlights the importance of cash conversion. Operating expenses declined 79% sequentially to $16.8 million, while adjusted EBITDA losses narrowed to $8.8 million from $42.7 million. A targeted $20 million budget for the 2027 Games, additional monetization channels and lower-cost Breakers events underpin management’s sports breakeven objective. Cash declined to $12.1 million, with $26 million of quarterly operating cash usage.
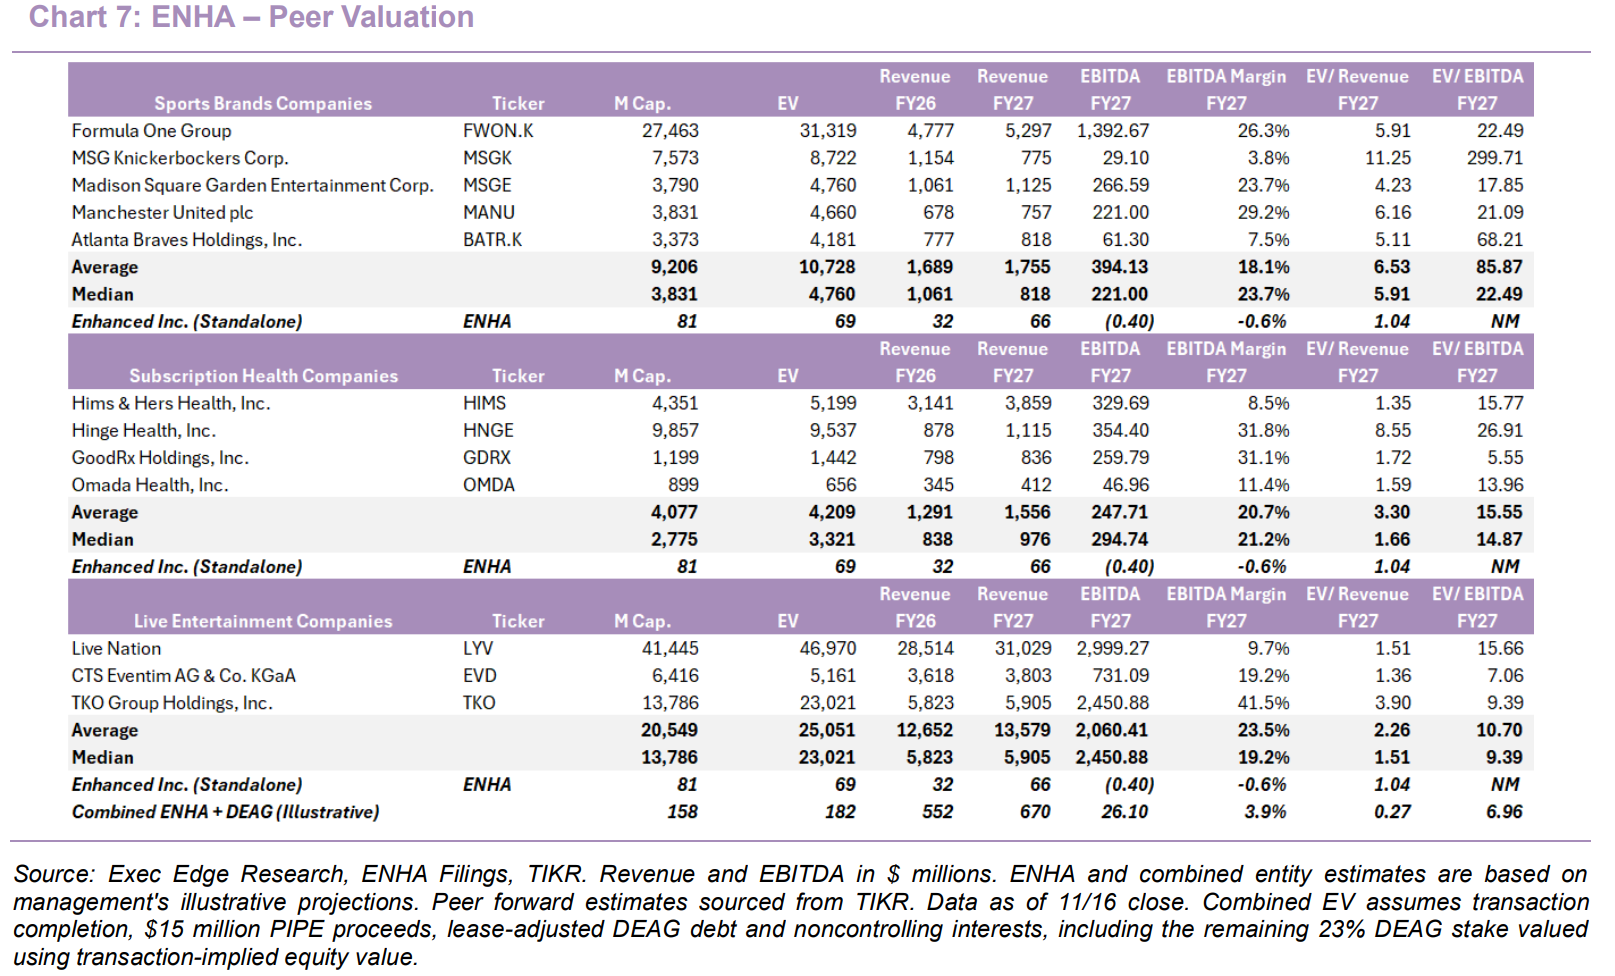
- ENHA’s valuation offers meaningful headroom as its sports IP, Live Enhanced consumer health platform and expanding live-entertainment presence demonstrate their earnings potential. While we do not have a price target or stock recommendation, we note that at an enterprise value of approximately $69 million, ENHA trades at just 1.04x 2027 target revenue, a discount to peers. The proposed DEAG acquisition further strengthens the valuation opportunity by adding an established earnings base and exposure to the live-entertainment sector at attractive acquisition multiples. Stronger Live Enhanced monetization, improving Games profitability and successful execution of the expanded entertainment strategy could support a valuation rerating.
DEAG Acquisition Transforms ENHA into a Diversified Live Entertainment Platform
- ENHA’s proposed acquisition of DEAG represents a major strategic transformation, adding an established European entertainment platform with substantial operating scale and a significantly larger earnings base. Announced November 5, the all-stock transaction will give ENHA an approximately 77% controlling interest in DEAG Deutsche Entertainment AG, with closing expected in 1Q27. DEAG operates across seven core European markets, stages approximately 6,000 live events annually and sells over 12 million tickets through its event and proprietary ticketing operations. Its portfolio spans concert touring, festivals, local promotion, spoken word and family entertainment, supported by more than 30 owned festival brands. The transaction values 100% of DEAG’s equity at approximately €100 million, or $115 million, based on €4.00 per share, implying a lease-adjusted enterprise value of approximately $139 million. The acquisition significantly diversifies ENHA beyond its flagship sporting events and early-stage consumer health business, establishing an integrated sports and live entertainment platform with a broader foundation for organic growth and acquisition-led expansion.
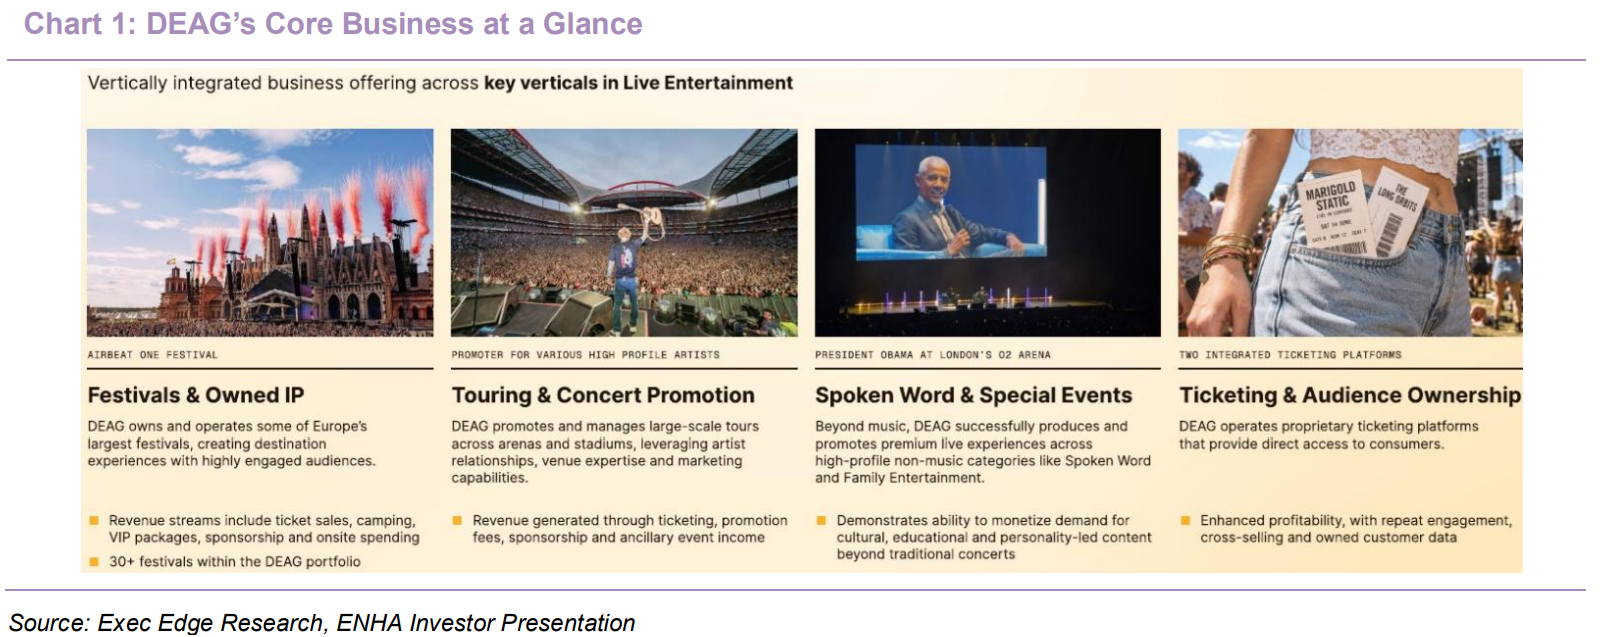
- ENHA’s expansion into live entertainment positions the company to capitalize on the growing experience economy, supported by structural demand for in-person events and shared experiences. Per the data cited in ENHA’s investor presentation, the global live events market is estimated at approximately $110 billion in 2025 and projected to grow at ~7% annually through 2030, reaching approximately $158 billion, driven by increasing attendance, pricing power and demand from younger consumers. Management believes advances in AI and automation will further reinforce demand for authentic, in-person experiences, creating a favorable backdrop for ENHA’s expansion beyond sports into music, festivals and other entertainment formats. DEAG’s established event infrastructure, proprietary IP and ticketing capabilities position ENHA to participate in this growth while pursuing consolidation opportunities across a fragmented market.
- DEAG brings an improving earnings profile, with higher-margin ticketing and spoken word businesses supporting disproportionate EBITDA growth. DEAG revenue is expected to increase from $520 million in 2026 to $604 million in 2027, while adjusted EBITDA is projected to rise from $13.6 million to $26.5 million, implying margin expansion from 2.6% to 4.4%. Touring and concert promotion account for approximately 54% of projected 2026 revenue but typically generate mid-single-digit EBITDA margins, whereas ticketing and spoken word can generate margins exceeding 20%. The projected earnings improvement therefore reflects growth in concert promotion alongside an increasing contribution from higher-margin businesses. For ENHA, this adds an established earnings-generating platform, providing a more diversified foundation for profitability while reducing dependence on the earnings inflection of its developing sports and telehealth businesses.
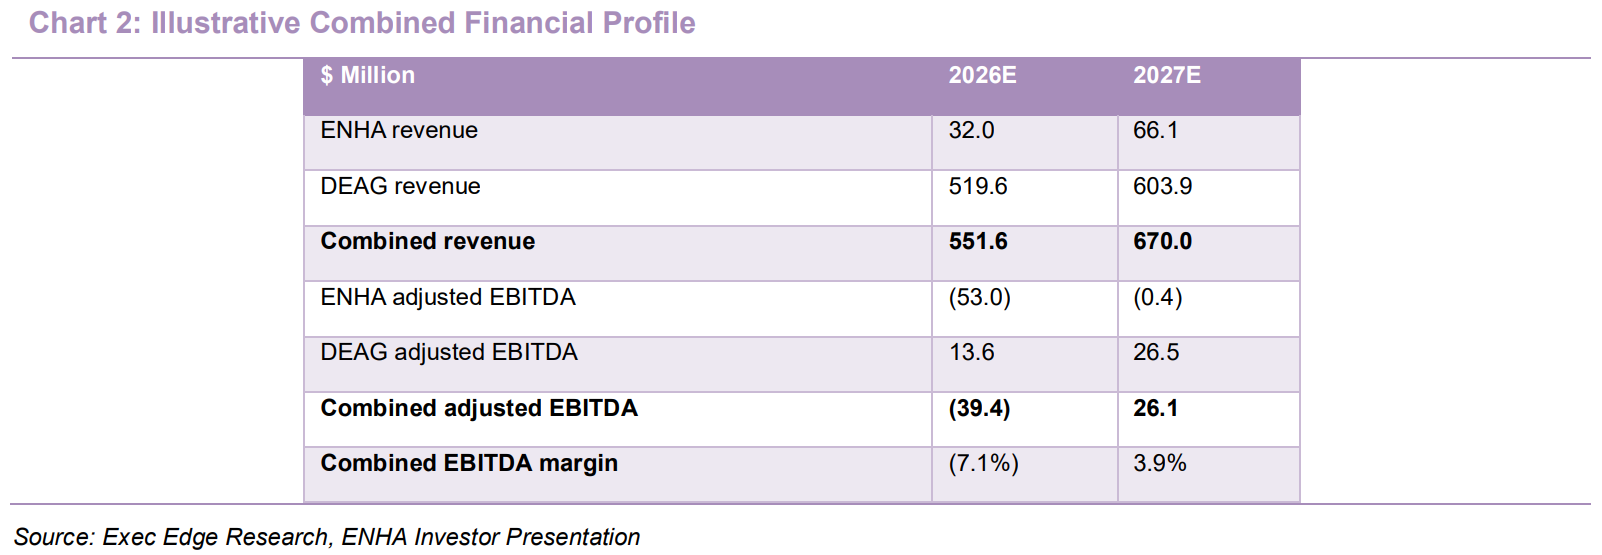
- The acquisition fundamentally changes ENHA’s forward financial profile, with the combined platform expected to transition toward positive adjusted EBITDA in 2027. On an illustrative combined basis, management expects revenue to increase 21.5% to $670 million in 2027 from $552 million in 2026, while adjusted EBITDA is projected to improve by approximately $65.5 million, from a loss of $39.4 million to positive $26.1 million. Of this improvement, approximately $52.6 million is expected from ENHA’s existing operations approaching breakeven, while DEAG contributes an incremental $12.9 million through earnings growth. The combined EBITDA margin is expected to improve from negative 7.1% to positive 3.9%, with the outlook excluding potential synergies. The projected earnings inflection reflects both a substantial normalization of ENHA’s operating cost structure and DEAG’s established profitability, with DEAG providing substantially all of the combined group’s positive EBITDA in 2027, while ENHA’s existing businesses approach breakeven.
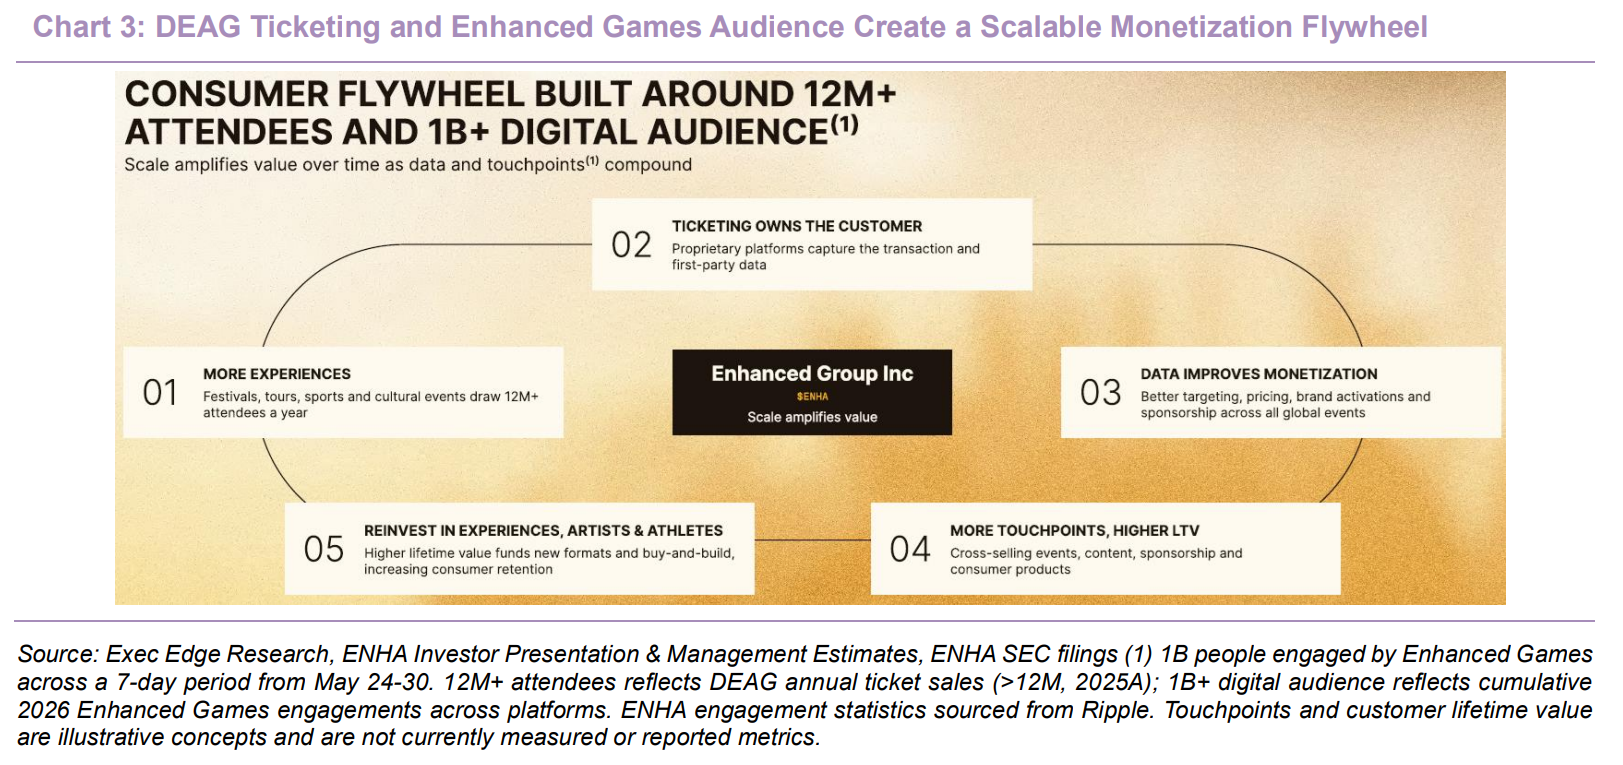
- DEAG’s ticketing infrastructure and acquisition capabilities create additional opportunities for operating efficiency, consumer distribution and consolidation. Its proprietary platforms, including myticket and Gigantic, complement established event production teams, venue relationships and sponsorship networks, potentially reducing external production and distribution costs for Enhanced Games and Breakers. Longer term, DEAG’s more than 12 million annual ticket sales create additional consumer touchpoints for Live Enhanced, including event-related supplements and recovery products, extending ENHA’s original audience-to-consumer monetization strategy across a much larger entertainment ecosystem. DEAG has completed more than 30 acquisitions since 2019 and has identified ~20 additional opportunities, providing an established platform for bolt-on acquisitions across promoters, festivals and ticketing, while ENHA separately targets larger platform acquisitions across sports, entertainment and consumer health. DEAG will retain its operating leadership, supporting continuity in execution. Together, the operating infrastructure, proprietary distribution and two-tier acquisition strategy position ENHA to pursue both organic expansion and consolidation across the fragmented live entertainment market.
- The all-stock transaction preserves cash at closing but materially increases ENHA’s economic share count, with the concurrent PIPE providing additional growth capital. The acquisition involves approximately 10.97 million new Class A shares, at an exchange ratio of approximately one ENHA share for every 1.7 DEAG shares, while the $15 million PIPE at $7.11 per share adds another 2.11 million shares. Based on the November 12 Class A share count of 13.81 million, the transactions imply approximately 26.89 million pro forma economic shares, with legacy ENHA shareholders retaining roughly 51% of the expanded Class A equity base before other potential issuances. The consideration shares are subject to staggered lockups through January 2028, with provisions for accelerated release based on share price performance. The transaction is expected to close in 1Q27, subject to customary conditions, with the PIPE closing concurrently. The structure preserves near-term liquidity and provides incremental capital to support the enlarged platform, while the issuance of approximately 13.1 million new shares represents substantial dilution to existing shareholders.
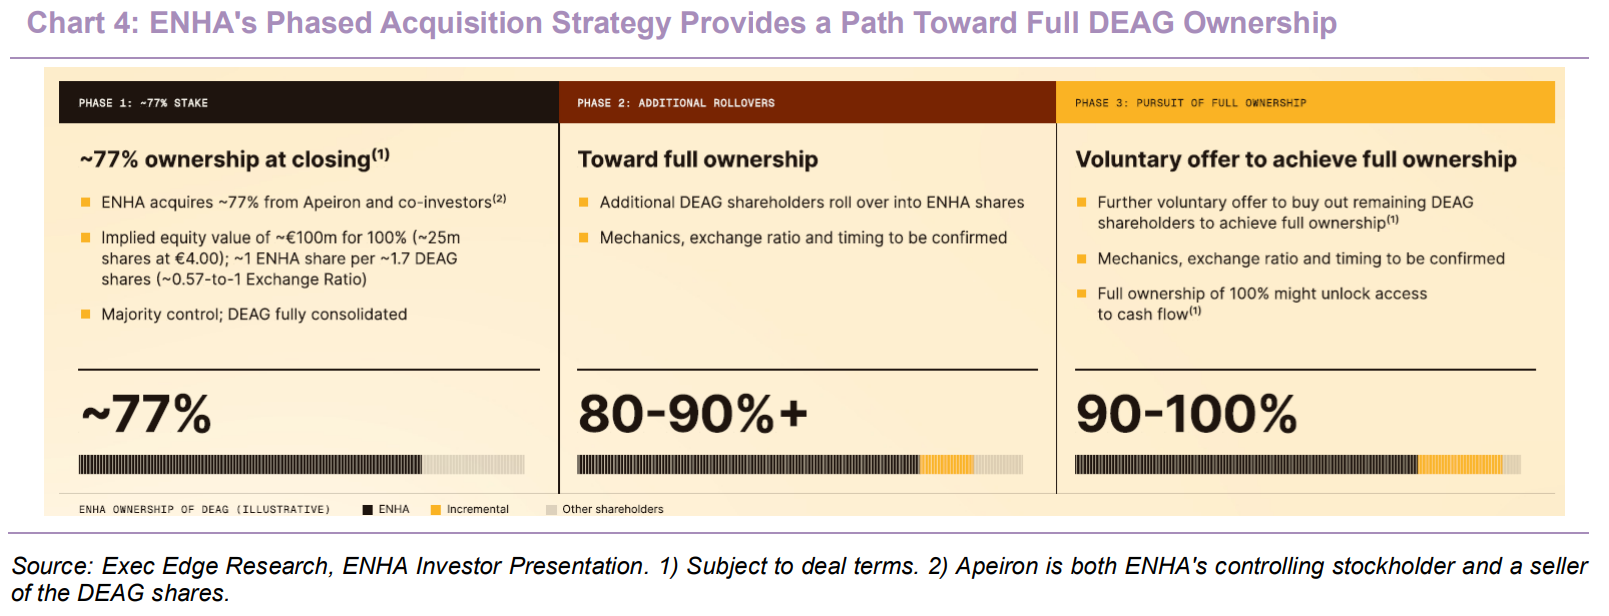
- ENHA’s phased acquisition strategy provides a path toward full DEAG ownership, with important implications for earnings attribution and cash flow access. The initial 77% stake provides majority control and full financial consolidation, while subsequent phases envisage additional DEAG shareholders exchanging their holdings for ENHA equity, potentially increasing ownership to 80-90% or more, followed by a voluntary offer targeting 100% ownership. Greater ownership would increase the proportion of DEAG earnings attributable to ENHA shareholders, while full ownership could improve access to DEAG’s operating cash flows, subject to existing debt arrangements. The staged structure allows ENHA to establish control at closing while retaining flexibility over the timing and consideration for further ownership consolidation.
3Q26 Earnings Review: Consumer Traction Improves as Operating Costs Normalize
- ENHA’s revenue mix is beginning to shift from Games sponsorships toward recurring consumer monetization, with Live Enhanced emerging as the key organic growth driver. Revenue totaled $3.3 million versus $17.7 million in 2Q26 and zero a year ago, reflecting the absence of inaugural Games-related revenue. Sponsorship arrangements with Rezolve and Rumble contributed $2.6 million, while Live Enhanced generated $0.7 million versus $0.2 million sequentially. Rezolve accounted for $1.9 million, including $1.2 million of accelerated recognition following an August contract amendment. Outstanding sponsorship obligations declined to $1.9 million from $4.5 million at June-end. Despite $32 million in inaugural Games sponsorship contract value, noncash consideration remains significant, making growth in cash-generating consumer revenue increasingly important.
- Live Enhanced’s first full commercial quarter demonstrates early traction in prescription-led consumer monetization, with growing demand supporting the platform’s scaling potential. Gross revenue increased 175% to $1.1 million from $0.4 million in 2Q26, marking the platform’s first full commercial quarter. Clinical services, including hormone therapies, peptides and longevity protocols, generated $0.9 million, while Stronger+ and Longer+ supplements contributed $0.2 million. After deducting approximately $0.4 million retained by independent third-party telehealth providers, recognized revenue totaled $0.7 million. Clinical services represented 82% of gross consumer revenue, establishing prescription offerings as the principal monetization engine. The partner-enabled model allows ENHA to focus on distribution and customer relationships without directly operating the clinical service network, providing a relatively capital-light foundation for scaling the consumer business as customer acquisition and recurring demand increase.
- Live Enhanced’s improving marketing productivity supports a more disciplined customer acquisition strategy ahead of broader commercialization. Performance marketing spend totaled $1.5 million versus $1.6 million sequentially, while gross consumer revenue increased 175%, lifting gross revenue per marketing dollar from $0.25 to $0.73. Management attributed the nearly threefold improvement to better acquisition efficiency and growing repeat and subscription activity. ENHA deliberately limited marketing expansion ahead of Enhanced OS, prioritizing product refinement and unit economics. Planned marketing acceleration will target women and longevity-oriented consumers through athlete and creator partnerships, supported by a brand refresh and the January 2027 Enhanced OS launch.
- Enhanced OS shifts Live Enhanced beyond individual product sales toward a continuously personalized health platform with recurring monetization potential. Launched in invitation-only beta on November 12, with broader commercialization planned for January 2027, the platform integrates medical records, wearable data and testing across more than 100 biomarkers into clinician-supervised health protocols. Recommendations span 30-, 60- and 100-day phases and evolve with updated health data. A planned $199 annual membership adds recurring revenue potential alongside diagnostics, supplements and prescription products, with prescription integration targeted for January. Drawing on hundreds of protocol adjustments developed during the inaugural Games’ athlete program, Enhanced OS uses proprietary data to differentiate its AI-driven recommendations and potentially improve engagement, retention and customer lifetime value.
- Live Enhanced’s expanding prescription portfolio broadens its addressable market, while clinician-guided protocols and personalization strengthen its competitive positioning. Following the October 28 HHS interim enforcement policy, ENHA added Modafinil and six peptides to its existing 12 prescription products, broadening offerings across metabolic regulation, hormone optimization, cognitive performance and recovery, while supplements are available across 33 international markets. The new peptides are offered through licensed clinicians and U.S. compounding pharmacies, with the policy permitting qualifying compounding activity under specified conditions rather than constituting FDA approval. ~85% of surveyed customers identified trust as a primary purchasing consideration, reinforcing the importance of clinician-guided recommendations. Broader product offerings, combined with Enhanced OS, create opportunities to increase products per customer, repeat purchasing and lifetime value, while differentiating ENHA beyond individual treatments.
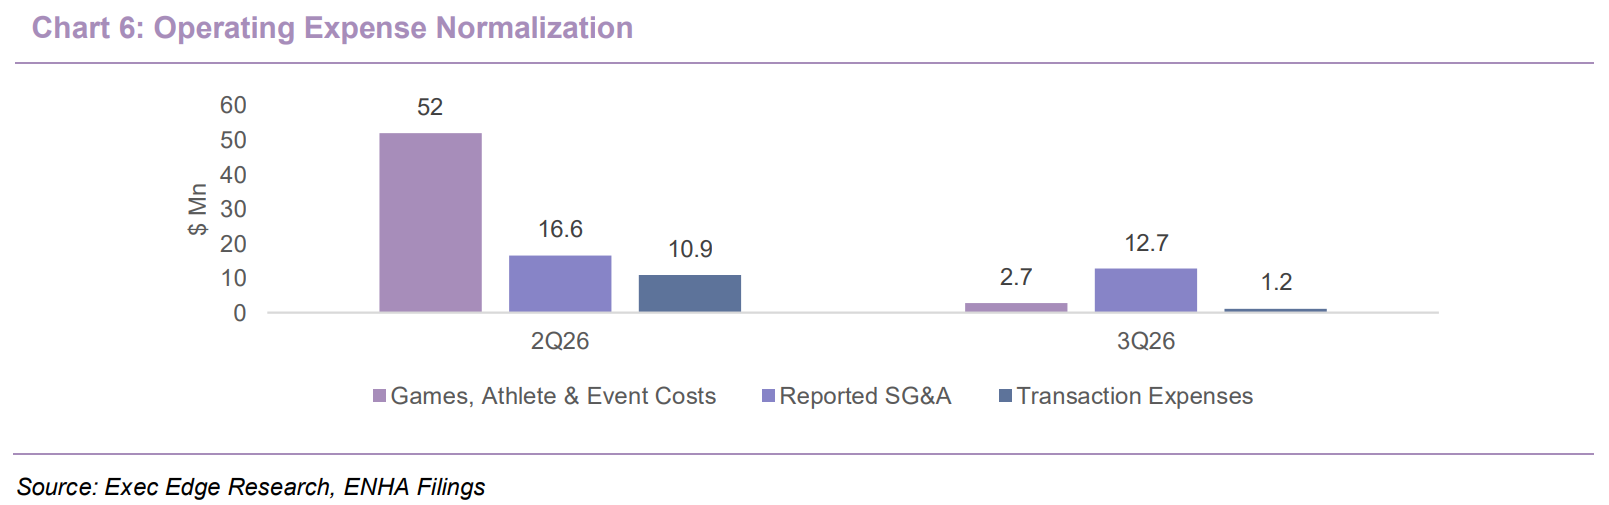
- Enhanced Games is transitioning toward a lower-cost, more commercially diversified model, supporting management’s targeted 2027 sports breakeven. Games and event expenses declined to $2.7 million in 3Q26 from $52 million in 2Q26, while the 2027 flagship event targets a $20 million budget through a three-hour format versus six hours previously, fewer competitions and athletes, reduced prize money and lower production costs. Reusable infrastructure, including $5.25 million of sporting equipment, should further limit investment. WME is leading sponsorship and media-rights efforts, alongside planned ticketing and potential host-city funding. The combination of lower production costs and broader monetization opportunities underpins management’s expectation of breakeven or better for Games and Breakers in 2027.
- Breakers extends the Enhanced Games franchise into a year-round, lower-cost content and audience acquisition platform. The inaugural July event featured Beatriz Pirón setting a snatch world record following injury, while Breakers 2 is scheduled for December 19 in Las Vegas, featuring eight swimmers. A third event is planned for 1Q27, establishing a more frequent competition calendar. Two-time Olympic gold medalist Hunter Armstrong joined the athlete roster in October. ENHA is also exploring partnerships with established triathlons and endurance races, leveraging existing event infrastructure. Together, these initiatives could broaden audience engagement between flagship Games and provide lower-cost customer acquisition opportunities for Live Enhanced.
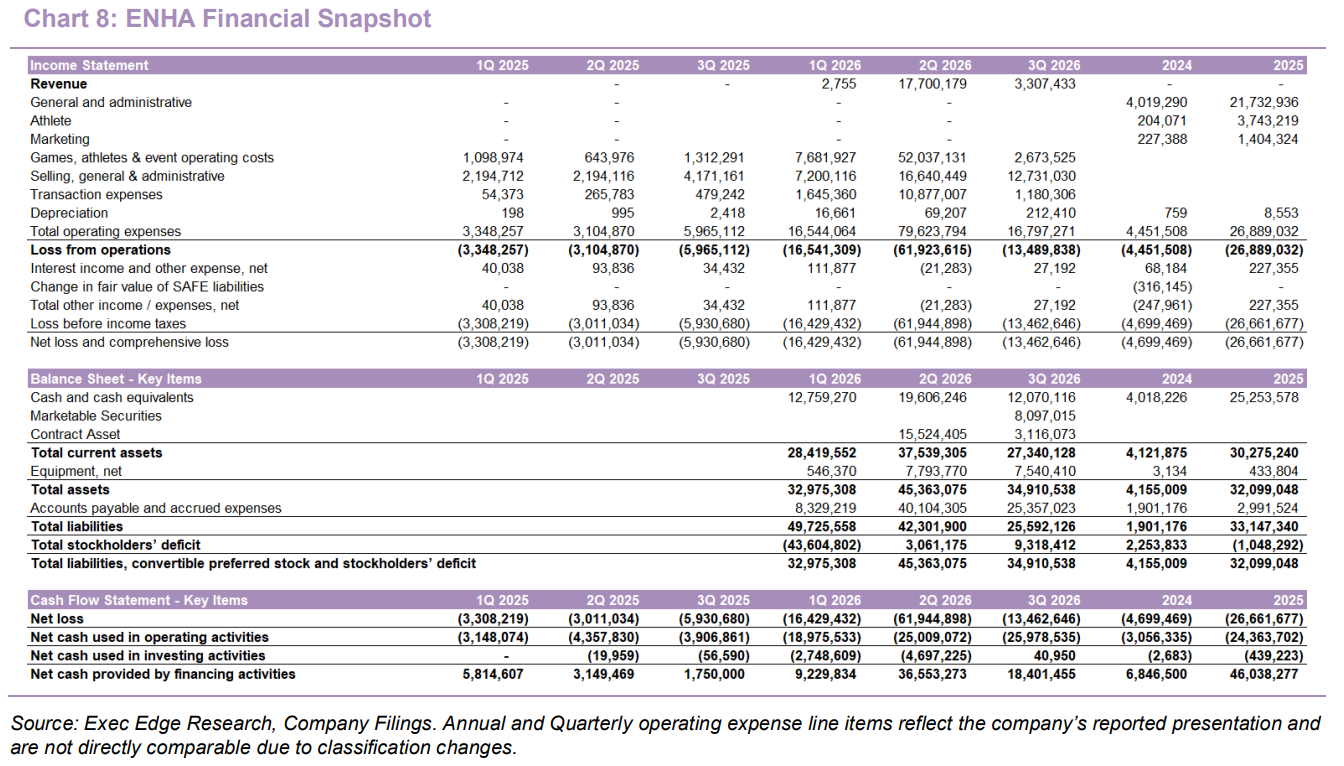
- The post-Games expense reset has materially reduced ENHA’s operating cost base, although public-company overhead remains elevated. Total operating expenses declined 79% to $16.8 million in 3Q26 from $79.6 million in 2Q26, supported by lower event spending and transaction expenses declining to $1.2 million from $10.9 million. SG&A decreased to $12.7 million from $16.6 million sequentially but remained above $4.2 million a year ago, reflecting higher public-company costs. Third-quarter SG&A included $3.1 million of noncash Rumble advertising expense, $1.5 million of stock-based compensation and $0.3 million of other one-time items, leaving underlying SG&A of $7.8 million versus $5.5 million in 2Q26. Higher audit, legal and compliance expenses contributed to the 42% sequential increase in underlying SG&A, highlighting the elevated recurring overhead that consumer growth and event monetization must absorb.
- Adjusted EBITDA losses narrowed substantially, but the underlying earnings trajectory remains dependent on revenue scaling against higher fixed costs. Operating and net losses narrowed to $13.5 million from $61.9 million sequentially, although net loss widened from $5.9 million a year ago, with diluted EPS of $(1.01) versus $(0.58) in 3Q25. Adjusted EBITDA loss improved to $8.8 million from $42.7 million sequentially, compared with $3.8 million a year earlier. Importantly, adjusted EBITDA still includes the $3.1 million noncash Rumble marketing expense. While the $33.9 million sequential improvement in adjusted EBITDA primarily reflects the roll-off of inaugural Games spending, the next phase of margin improvement must come from recurring consumer revenue growth, commercial monetization of future events and disciplined overhead management.
- Cash consumption remains elevated despite narrowing operating losses, as settlement of inaugural Games obligations continues to absorb liquidity. Cash declined to $12.1 million at September-end from $19.6 million in June and $25.3 million at year-end 2025. Operating cash outflows totaled $70.0 million in 9M26 versus $11.4 million a year ago, implying approximately $26 million of 3Q cash usage, well above the $8.8 million adjusted EBITDA loss. Accounts payable and accrued expenses declined to $25.4 million from $40.1 million sequentially, with approximately $11.7 million remaining Games-related, underscoring the continuing cash burden of the inaugural event.
- Working capital remains constrained by noncash sponsorship assets, while infrastructure investments should reduce future event costs. ENHA’s partner-led clinical model carries no separately material inventory balance, although $8.1 million of Rezolve securities, a $1.9 million related receivable and noncash Rumble advertising assets limit immediate liquidity. Investing cash outflows totaled $7.4 million in 9M26, including $5.4 million of equipment purchases and $2.0 million of capitalized internal-use software, supporting reusable Games infrastructure and digital event capabilities.
- Potential financing and sponsorship proceeds could materially strengthen liquidity, although their timing and realization remain uncertain. Following the completion of the $50 million private placement in August, ENHA expects an additional $15 million PIPE alongside the DEAG closing, potential proceeds of approximately $10 million from Rezolve securities following the December 23 lockup expiration, and a $10 million Zoop sponsorship payment due at year-end. Including September cash, these sources represent approximately $47 million of potential liquidity, although the PIPE is conditional on the DEAG closing, Rezolve monetization depends on market conditions and resale restrictions, and Zoop collection had not been deemed probable as of September 30. The September 10-Q continues to identify substantial going-concern uncertainty. With capital required for Enhanced OS, future Games and acquisitions, improving cash generation and disciplined deployment remain critical to execution.
- ENHA’s standalone operations are projected to approach breakeven in 2027, supported by lower Games costs and improving Live Enhanced economics. Management’s November 5 illustrative projections anticipate revenue increasing from $32.0 million in 2026 to $66.1 million in 2027, up 107%, compared with Street estimates of $28.0 million and $61.4 million, respectively, sourced from TIKR. Adjusted EBITDA is projected to improve from a loss of $53.0 million to near breakeven at $(0.4) million, versus Street estimates of losses of $71.8 million and $4.0 million, respectively. The improvement reflects a substantially lower-cost Games format, targeted sports breakeven in 2027, and growing Live Enhanced monetization, with the consumer business targeting profitability by year-end 2026. While the 2026 baseline implies a substantial fourth-quarter recovery relative to reported nine-month results, management’s 2027 outlook is modestly above consensus on revenue but materially more optimistic on profitability, placing greater emphasis on execution and cost discipline.
- The DEAG acquisition fundamentally changes ENHA’s earnings profile, with established entertainment operations providing the foundation for positive consolidated EBITDA in 2027. Illustrative combined revenue is projected to increase 21.5% from $551.6 million in 2026 to $670.0 million in 2027, while adjusted EBITDA improves from a $39.4 million loss to positive $26.1 million, lifting margins from negative 7.1% to 3.9%. DEAG contributes $26.5 million of projected 2027 adjusted EBITDA versus a $0.4 million standalone ENHA loss, making it the principal source of combined profitability. Management reaffirmed the approximately $670 million revenue and $26 million adjusted EBITDA targets on its 3Q26 earnings call. Projections assume full DEAG consolidation, exclude synergies and depend on closing.
Attractive Acquisition Economics and Expanded Earnings Base Support Rerating Potential
- Disclaimer: Exec Edge does not publish proprietary estimates, ratings, price targets, or investment recommendations. The valuation discussion below is illustrative only and is based on company filings, management commentary, and third-party data and estimates. It does not constitute a recommendation, price target, rating, or prediction of future pricing.
- ENHA’s standalone valuation offers meaningful scope for rerating as its sports IP and consumer health platform scale. As of 11/16 close, ENHA has a market capitalization of approximately $81 million and enterprise value of $69 million. The stock trades at 1.04x management’s illustrative 2027 revenue of $66.1 million, compared with median EV/revenue multiples of 5.91x for selected sports brands and 1.66x for subscription-health peers. The valuation gap highlights the potential for stronger Live Enhanced monetization, expanding recurring consumer revenue and improved Games economics to support a higher multiple as both businesses mature.
- The DEAG acquisition introduces an established earnings base at an attractive entry valuation, materially changing ENHA’s pro forma trading multiples. The issuance of 10.97 million acquisition consideration shares and 2.11 million PIPE shares would increase economic shares outstanding to approximately 26.89 million, implying a $157.6 million market capitalization and $181.6 million lease-adjusted enterprise value at the current stock price. Against management’s illustrative 2027 projections of $670 million in revenue and $26.1 million in adjusted EBITDA, the combined entity would be valued at 0.27x revenue and 6.96x EBITDA, compared with live-entertainment peer medians of 1.51x and 9.39x, respectively. DEAG’s acquisition valuation of approximately 5.3x projected 2027 adjusted EBITDA further supports the favorable entry economics. However, the combined group’s projected 3.9% EBITDA margin remains below the 19.2% peer median, explaining part of the valuation discount and underscoring the importance of improving business mix and operating leverage. The pro forma EV includes DEAG’s remaining 23% minority interest and assumes transaction completion and receipt of the $15 million PIPE proceeds.
- We see scope for valuation rerating as DEAG adds earnings scale and ENHA progresses toward sustainable profitability across its sports and consumer businesses. DEAG’s higher-margin ticketing and spoken word operations offer opportunities for margin expansion, while the targeted $20 million Games budget, 2027 sports breakeven and Enhanced OS commercialization could improve ENHA’s standalone earnings contribution. Successful integration, delivery against the combined $670 million revenue and $26.1 million adjusted EBITDA outlook, and stronger cash conversion would provide the clearest catalysts for narrowing the valuation discount. Transaction-related dilution, remaining minority interests and ongoing liquidity requirements could temper rerating until the expanded platform demonstrates sustainable cash generation.
Read Exec Edge’s Initiation on Enhanced Group, Inc. Here
Enhanced CEO Maximilian Martin & CFO Sid Banthiya, Live at NYSE
Enhanced CEO Maximilian Martin on Enhanced Games: ICR Conference 2026
Subscribe to our Weekly Newsletter to Receive All Research
Contact: