Download the Complete Report Here
AIR Global PLC (AIIR)
Shipment Recovery Drives Double-Digit Growth; Crown Switch Progress and Shareholder Returns Strengthen Investment Case. Valuation Remains Attractive.
- Key Takeaways:
- FSM shipments rebounded 5.8% y/y, driving 11.1% revenue growth as supply-chain normalization and resilient consumer demand supported recovery.
- Americas led revenue growth at 25.6%, although regional EBITDA declined 3.6% as elevated input costs constrained earnings conversion.
- Crown Switch PMTA submission marks a major regulatory milestone, with a more focused NGC strategy prioritizing disciplined investment and sustainable profitability.
- The $425 million refinancing and planned dividends and buybacks strengthen financial flexibility and shareholder returns, while 2026 leverage expectations rise to 2.5x from 2.1x.
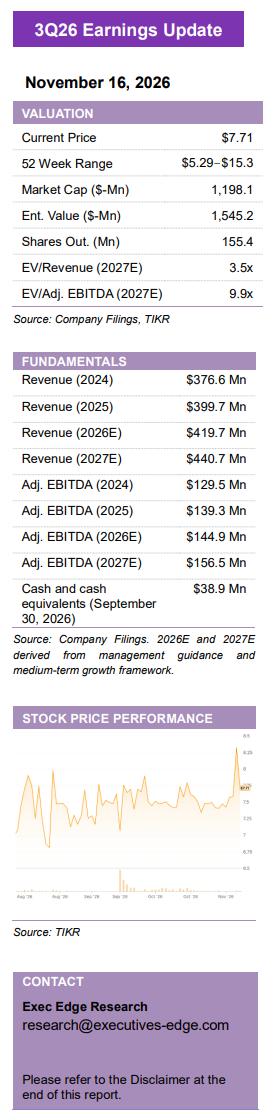
- At 9.9x 2027E EBITDA, a roughly 13% discount to peers, valuation remains attractive, with earnings normalization, deleveraging and NGC commercialization supporting rerating potential.
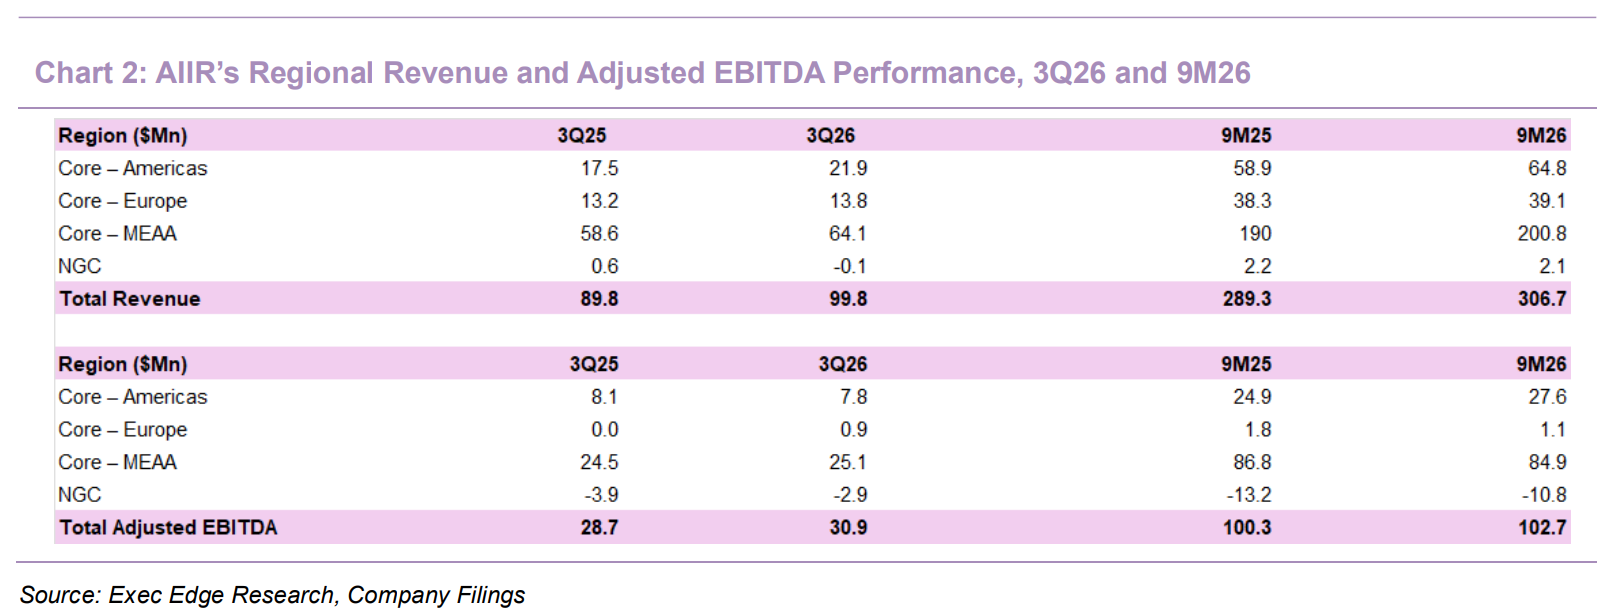
- Strong shipment recovery drove double-digit revenue growth, reinforcing AIIR’s core business resilience and transition toward volume-led growth. AIR Global reported 3Q26 revenue of $99.8 million, up 11.1% y/y, supported by 5.8% growth in flavored shisha molasses (FSM) shipment volumes and 5.0% price/mix. Adjusted EBITDA increased 7.7% to $30.9 million, with elevated logistics, raw-material and manufacturing costs limiting earnings conversion. For 9M26, revenue increased 6.0% to $306.7 million, while adjusted EBITDA grew 2.3% to $102.7 million, reflecting the earlier supply-chain disruption. The return to positive shipment growth following the first-half disruption supports management’s reiterated 2026 outlook and reinforces confidence in underlying consumer demand.
- Sustained pricing power and recovering shipments position AIIR for more balanced, volume-led growth. FSM shipment volumes rebounded 5.8% in 3Q26 following a 9.0% decline in 1H26, while price/mix moderated to 5.0% from an exceptional 14.0%. For 9M26, volumes remained down 4.6%, offset by 11.1% price/mix growth. Further shipment recovery is expected in 4Q26, with channel inventories anticipated to normalize by year-end. Importantly, double-digit nine-month price/mix growth without meaningful share erosion underscores Al Fakher’s brand strength, supported by 36% to 44% market share across operating markets and approximately 60% to 65% in the U.S. Relatively low annual U.S. shisha expenditure of approximately $110, versus $400 for nicotine pouches and $1,000 to $2,200 for vaping and cigarettes, provides additional pricing headroom. With further pricing actions planned for 2027, AIIR remains positioned to sustain value-led growth alongside normalized shipment expansion.
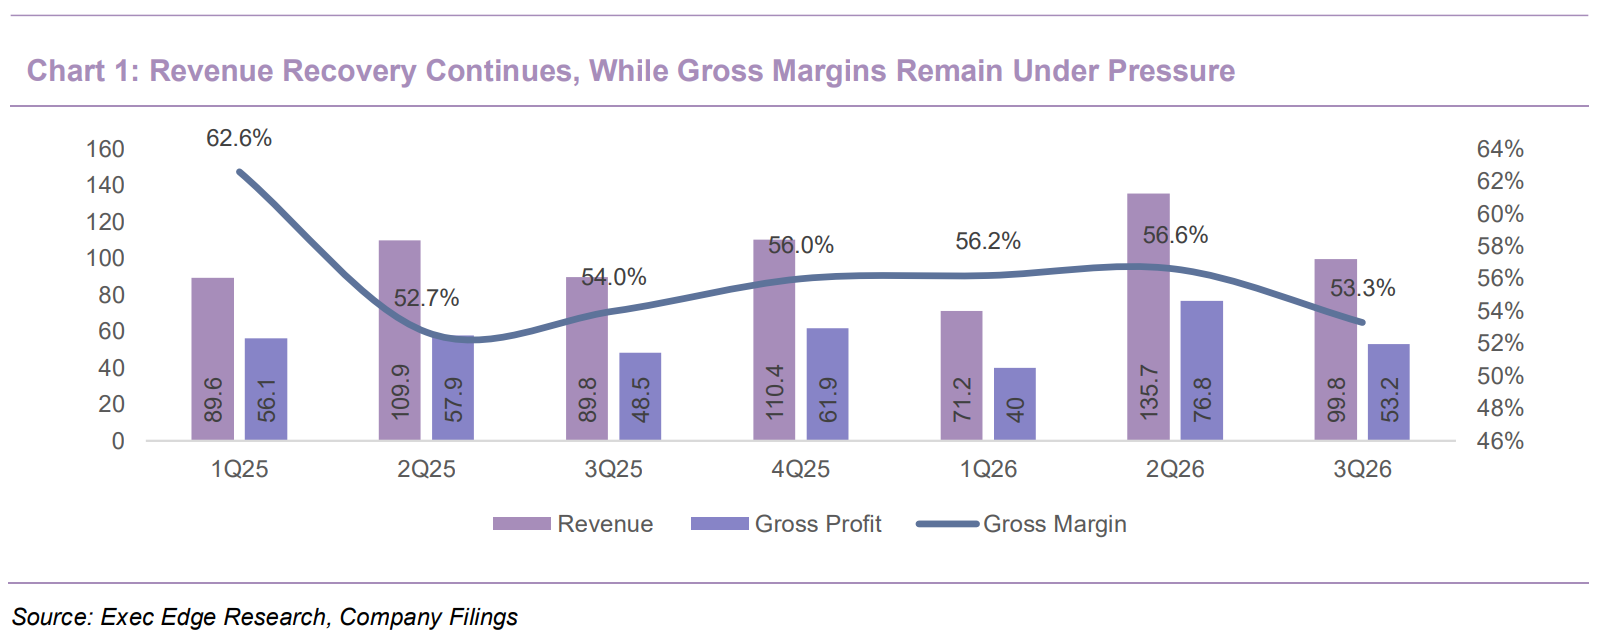
- Supply-chain diversification has restored shipment momentum, with cost normalization offering meaningful margin upside. Following the Strait of Hormuz disruption, which historically affected approximately 70% of shipments, AIIR established alternative routes through Oman and Saudi Arabia and accelerated manufacturing diversification. These measures supported the 3Q26 volume recovery, while elevated shipping, energy, insurance and raw-material costs continue to pressure margins. U.S.-bound production has also shifted toward Poland, increasing inventory requirements, while the Romania facility remains on track to commence operations in 1Q27, further reducing supply-chain concentration. The reconfigured network should improve resilience, while pricing actions and eventual cost normalization offer potential for approximately 300 bps of gross margin recovery over time.
- Americas remains AIIR’s primary growth driver, with margin recovery offering the next earnings catalyst. Revenue increased 25.6% y/y to $21.9 million in 3Q26, driven by 28.5% shipment volume growth, partially offset by negative 2.3% price/mix due to trade incentive timing. Adjusted EBITDA declined 3.6% to $7.8 million, with margin contracting to 35.6% from 46.3% due to higher cost of goods sold. Al Fakher’s estimated 60% to 65% U.S. market share, established retail and lounge distribution, and continued premiumization support the region’s growth outlook, while margin recovery will depend on easing input costs and improved pricing realization.
- MEAA remains AIIR’s core earnings engine, with sustained pricing power supporting growth and margin recovery. Revenue increased 9.4% y/y to $64.1 million in 3Q26, supported by 3.0% shipment volume growth and 6.2% price/mix, while adjusted EBITDA rose 2.4% to $25.1 million. Margin moderated to 39.2% from 41.8%, reflecting higher logistics, material and public-company costs. Al Fakher maintains approximately 50% market share in Saudi Arabia, reinforcing its established brand leadership and competitive positioning. Sustained pricing and easing regional cost inflation remain key to margin recovery.
- Europe’s shipment recovery supported improved profitability, although excise taxes and illicit competition remain structural headwinds. Revenue increased 4.9% y/y to $13.8 million in 3Q26, with 6.9% shipment volume growth offset by negative 1.8% price/mix. Adjusted EBITDA improved to $0.9 million from breakeven, representing a 6.5% margin versus 0.4% in 1H26. Germany’s revised excise framework reduces regulatory uncertainty, with taxes set at €60/kg in March 2027 and €94.50/kg by 2030, versus an earlier proposal approaching €195/kg. Nevertheless, higher taxes could widen the legal-illicit price gap, making enforcement and pricing discipline critical to sustainable profitability.
- NGC strategy is becoming more focused and returns-driven, with Crown Switch emerging as AIIR’s principal growth priority. NGC reported negative $0.1 million of revenue in 3Q26 versus positive $0.6 million y/y, reflecting trade incentive timing, while its adjusted EBITDA loss narrowed to $2.9 million from $3.9 million on lower operating costs. For 9M26, revenue declined 2.6% to $2.1 million, while adjusted EBITDA losses narrowed to $10.8 million from $13.2 million. Management is prioritizing the U.S. rechargeable pod-vape market, where the industry leader is estimated by management to generate EBIT margins above 40%, supported by a more favorable competitive environment as enforcement against illicit vapes increases. In contrast, intensifying competition and pricing pressure in nicotine pouches have prompted a more selective investment approach. OOKA and functional inhalation remain longer-term opportunities, with Crown Switch now the principal near-term commercialization focus and management emphasizing sustainable profitability over revenue growth alone.
- Crown Switch’s PMTA submission advances AIIR’s U.S. vaping strategy, with regulatory progression the next catalyst for commercialization. AIR submitted its application in early November 2026, supported by extensive testing covering product quality, manufacturing, aerosol constituents and consumer behavior. The next milestone is FDA acceptance for scientific review, which management expects would enable a targeted U.S. launch under the applicable FDA enforcement framework, ahead of full marketing authorization. Tighter enforcement against illicit vaping products is expected to improve the competitive environment for authorized products, with management seeing scope for mid-teen U.S. rechargeable pod-vape revenue growth over the coming years as illicit products lose share. This positions Crown Switch to participate in an expanding legal vape market as it progresses through regulatory review.
- Greentank’s differentiated technology and Al Fakher’s established consumer reach provide a strong foundation for Crown Switch’s commercialization. AIR’s $20 million Greentank investment provides access to proprietary Quantum Chip technology and a long-term supply arrangement, while Al Fakher’s approximately 14 million global consumers and established retail and digital channels offer potential customer acquisition advantages. Crown Bar’s contribution of approximately 4% to 2025 revenue provides evidence of successful brand extension into vaping. Together, these capabilities position Crown Switch to build a recurring pod-revenue business, with consumer adoption and repeat purchases determining its scalability and profitability.
- Pricing actions and cost normalization could drive 50 to 100 bps of annual adjusted EBITDA margin expansion over the medium term. Gross profit increased 9.8% y/y to $53.2 million in 3Q26, while cost of sales rose 12.7%, reducing gross margin to 53.3% from 54.0%. Adjusted EBITDA margin moderated to 31.0% from 31.9%, reflecting higher logistics, raw-material and manufacturing costs alongside incremental public-company expenses. Further pricing actions in 2027 should help offset inflation, while eventual logistics normalization offers additional upside.
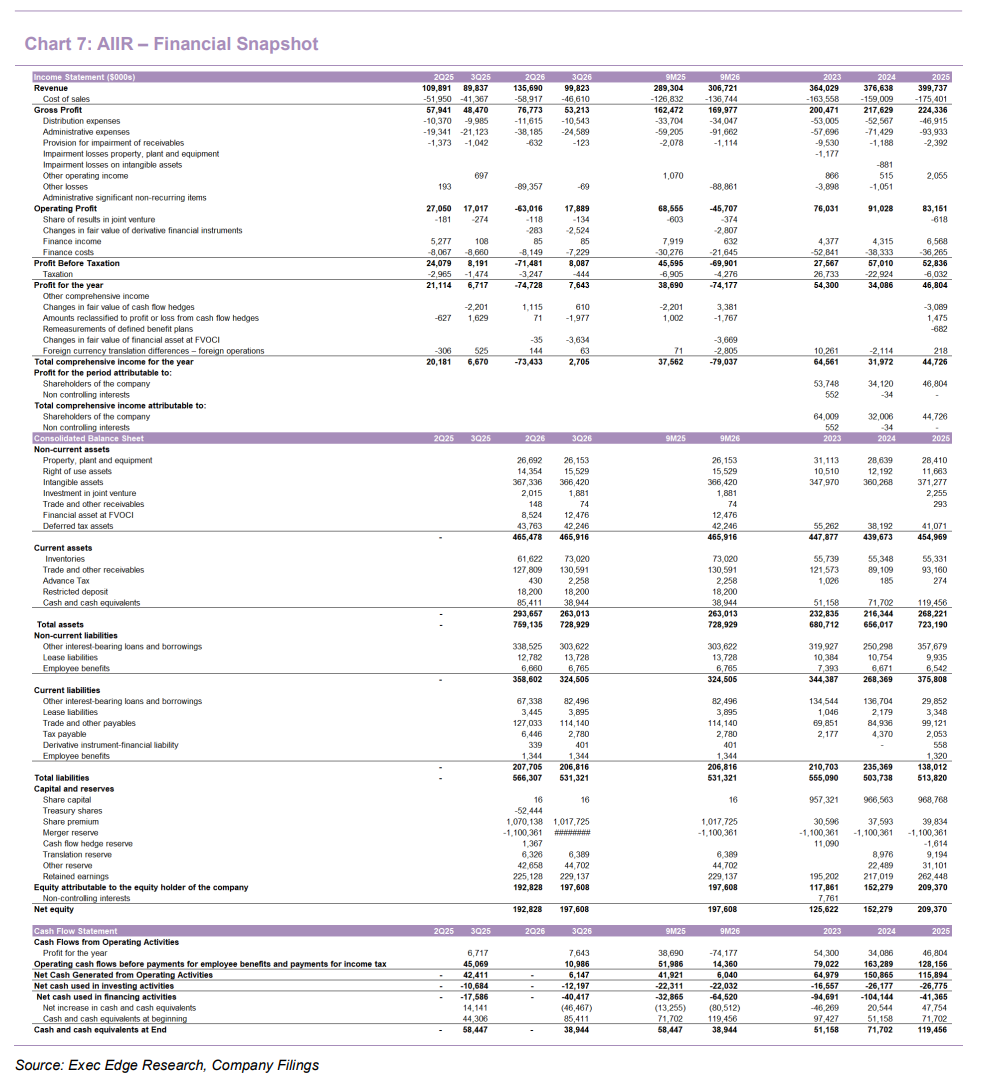
- Reported profitability should normalize as listing-related expenses roll off, improving earnings quality and visibility. Operating profit increased 5.1% y/y to $17.9 million, while net profit rose 13.8% to $7.6 million, with EPS increasing to $0.052 from $0.047. Reported EBITDA reached $23.7 million versus adjusted EBITDA of $30.9 million. For 9M26, AIR reported a $74.2 million net loss versus a $38.7 million profit y/y, despite $102.7 million of adjusted EBITDA. Listing-related expenses totaled approximately $106.3 million, including $48.2 million of noncash equity expense, $47.7 million of transaction fees and $10.5 million of public-company readiness costs. Additional adjustments included $14.1 million of share-based compensation and $3.4 million of PMTA costs. The roll-off of major listing expenses should narrow the gap between reported and adjusted earnings, although share-based compensation will continue through vesting.
- Working-capital normalization should drive a recovery in cash conversion through 2027 as supply-chain disruptions ease. Inventories increased to $73.0 million at September-end from $55.3 million at 2025-end and $61.6 million in June, reflecting higher raw-material buffers, alternative sourcing and the shift of U.S.-bound production toward Poland. Receivables rose to $130.6 million from $93.2 million at 2025-end, while payables declined sequentially to $114.1 million from $127.0 million, further absorbing cash. Consequently, operating cash flow declined to ~$6.0 million in 9M26 from $42.4 million a year earlier, while cash fell to $38.9 million from $119.5 million at 2025-end, also reflecting listing, strategic and financing outflows. The underlying cash-generation potential remains significant, with 2025 operating cash flow of $115.9 million representing 83% of adjusted EBITDA. Some inventory normalization is expected in 4Q26, with broader working-capital recovery extending into 2027.
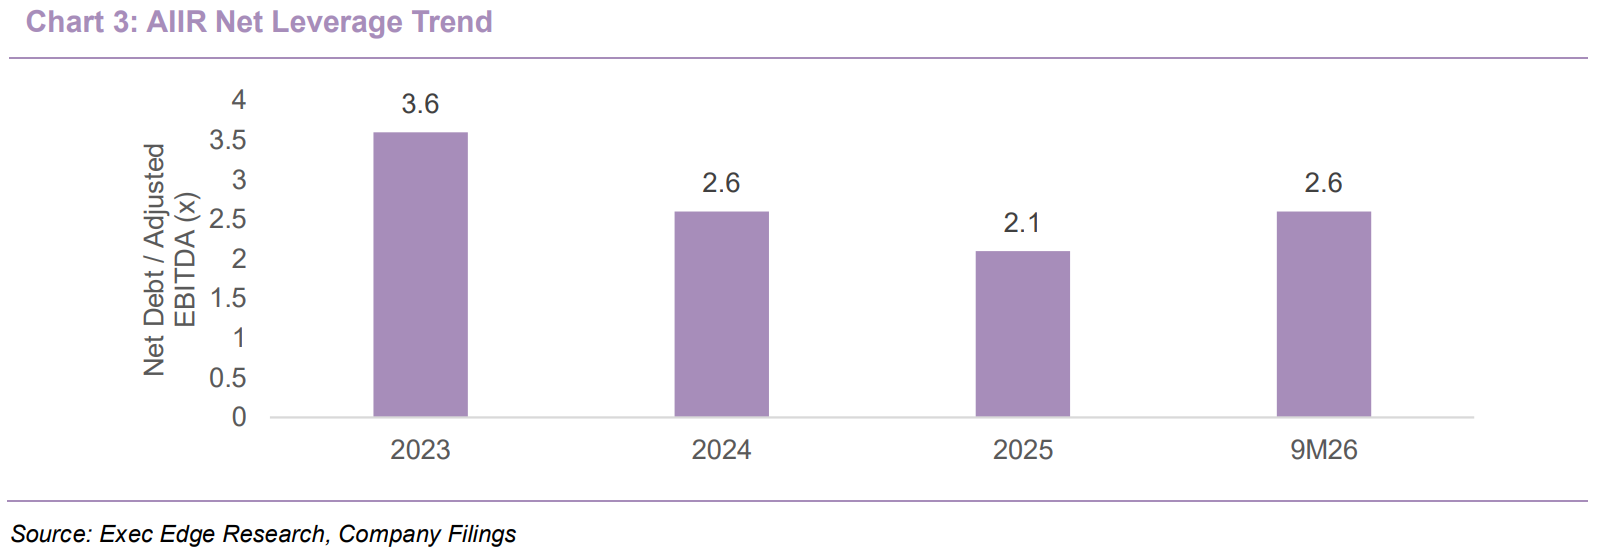
- Refinancing strengthens financial flexibility, while working-capital normalization and EBITDA growth support deleveraging toward 2.0x by 2027. Total borrowings including leases stood at $403.7 million at September-end, with net debt of $364.8 million and leverage of 2.6x trailing adjusted EBITDA of $141.6 million. Year-end leverage is now expected at approximately 2.5x versus 2.1x previously, with roughly two-thirds of the revision attributable to working capital and one-third to refinancing cash flows. On October 1, AIR completed a $425 million senior unsecured notes issuance at a 7.875% coupon, maturing in 2031, refinancing its term loan and revolving facility. The transaction extends maturities and improves funding visibility, with the September balance sheet reflecting the pre-refinancing debt structure. Supported by EBITDA growth and working-capital normalization, AIR continues to target leverage at or below 2.0x by December 2027, including planned shareholder returns.
- Formal shareholder returns add a new dimension to AIIR’s equity story, supported by its established cash-generation capacity. AIR plans an annual dividend of $0.28 per share, payable quarterly beginning with 1Q27 results, representing an indicated yield of approximately 3.6% at the $7.71 share price, with a progressive dividend policy thereafter. The company also intends to repurchase up to $100 million of shares through December 2029, equivalent to approximately 8.3% of its current market capitalization. Separately, the September settlement of the Harraden prepaid forward arrangement resulted in the cancellation of approximately 5 million shares, reducing outstanding shares to 155.39 million, including 8.69 million conditional earnout shares. The dividend represents an indicative annual commitment of approximately $43.5 million at the reported share count, with capital returns funded from equity free cash flow after capex, interest and lease payments, alongside continued investment and deleveraging toward the 2027 target.
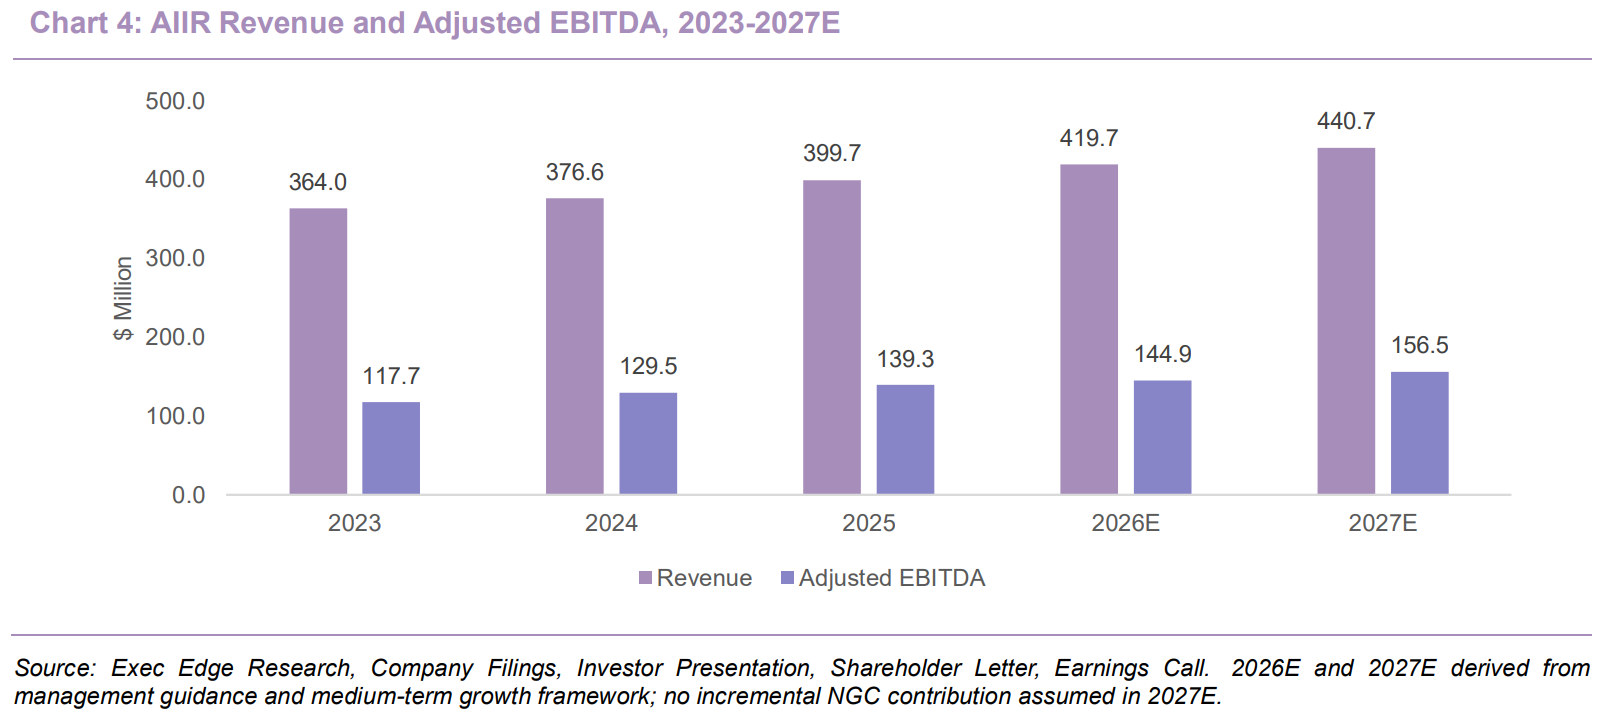
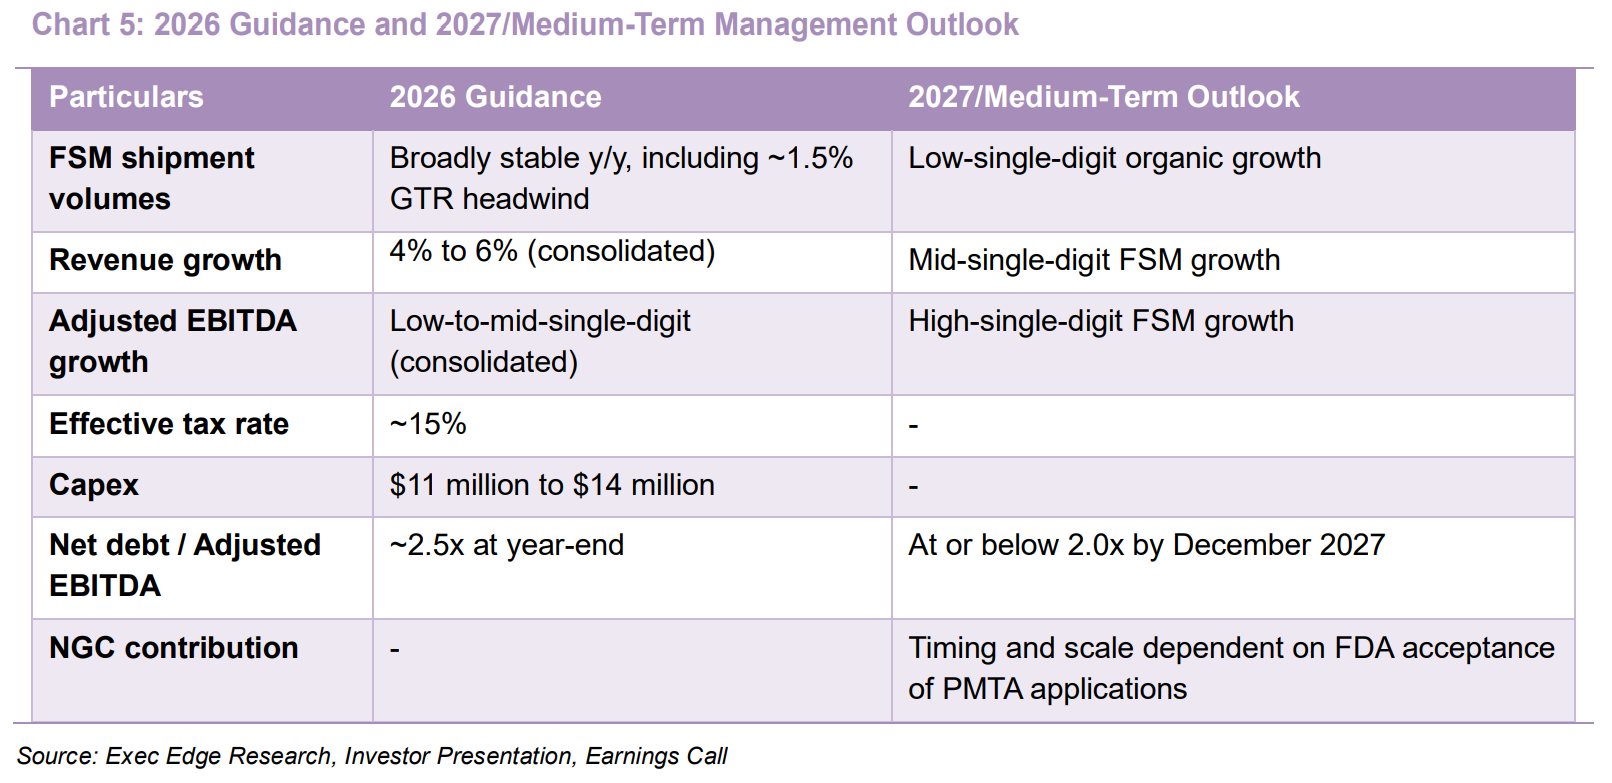
- Reiterated 2026 guidance reflects confidence in continued shipment recovery, with stronger fourth-quarter earnings conversion supporting the outlook. AIR reiterated 4% to 6% revenue growth and low-to-mid-single-digit adjusted EBITDA growth guidance, with broadly stable FSM shipment volumes despite a 1.5% Global Travel Retail headwind. Based on the midpoint of management’s guidance, 2026 revenue can be projected to reach $419.7 million (+5.0%) and adjusted EBITDA $144.9 million (+4.0%). Following 9M26 revenue of $306.7 million and adjusted EBITDA of $102.7 million, this implies 4Q26 revenue of $113.0 million and EBITDA of $42.2 million, requiring stronger earnings conversion as shipments recover. Street estimates (source: TIKR) remain more conservative at $415.4 million in revenue and $138.0 million in EBITDA, reflecting continued caution around elevated operating costs. Capex guidance was reduced to $11 million to $14 million from $15 million to $18 million, while the effective tax-rate outlook remains at 15%.
- Normalized volume growth, sustained pricing power and improving operating leverage position AIIR for stronger earnings growth in 2027. AIR reiterated medium-term expectations for low-single-digit FSM shipment volume growth, mid-single-digit revenue growth and high-single-digit adjusted EBITDA growth. Applying management’s growth framework, 2027 revenue can be projected to reach $440.7 million (+5.0%) and adjusted EBITDA $156.5 million (+8.0%), with EBITDA margin expanding to 35.5% from 34.5% in 2026E. Street estimates (source: TIKR) indicate higher revenue of $448.1 million (+7.9%) but lower EBITDA of $152.0 million (+10.1%), implying a more conservative margin outlook of 33.9%. The Romania factory opening in 1Q27, continued pricing actions, easing disruption costs and working-capital normalization should support earnings and cash-flow recovery. Crown Switch provides additional growth optionality, with no incremental NGC contribution assumed in the guidance-derived estimates. Improving cash generation should also support the target of leverage at or below 2.0x by December 2027.
Valuation Anchored by Core Earnings, with Upside from Normalization and NGC Optionality
- Disclaimer: Exec Edge does not publish proprietary estimates, ratings, price targets, or investment recommendations. The valuation discussion below is illustrative only and is based on company filings, management commentary, and third-party data and estimates. It does not constitute a recommendation, price target, rating, or prediction of future pricing.
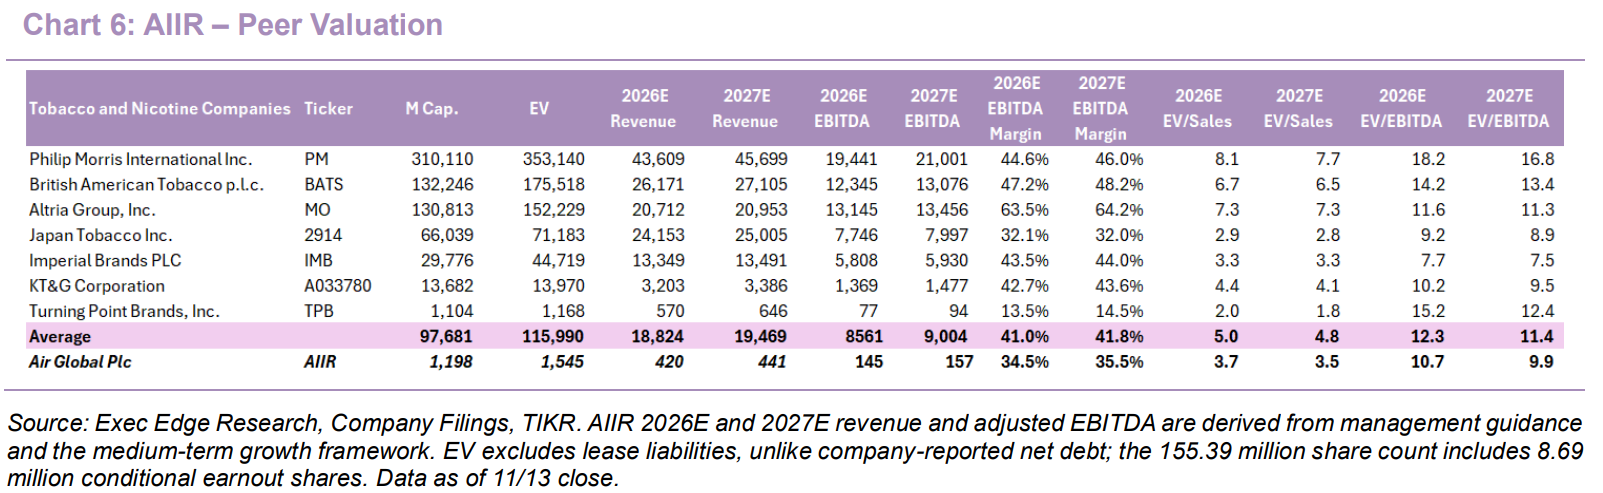
- AIIR’s resilient core earnings and improving growth visibility support a compelling valuation despite near-term margin pressures. At $7.71, AIIR has a market cap of approximately $1.20 billion and EV of $1.55 billion, ~12% below its original $1.75 billion SPAC transaction valuation. Based on estimates derived from management’s growth framework, the stock trades at 3.7x 2026E revenue and 10.7x EBITDA, declining to 3.5x and 9.9x, respectively, in 2027E. The core FSM franchise underpins valuation through established profitability, pricing power and cash-generation potential, with Crown Switch providing incremental upside rather than a necessary contribution to the earnings base. The discount to the original transaction valuation persists despite recovering shipments, sustained pricing power and a clearer shareholder-return framework, with improving earnings conversion offering further upside.
- AIIR trades at a discount to tobacco and nicotine peers despite stronger growth prospects, creating scope for rerating as margins normalize. AIIR trades at 10.7x 2026E and 9.9x 2027E EV/EBITDA versus peer averages of 12.3x and 11.4x, implying discounts of approximately 13% in both years. The discount is more pronounced on EV/Sales, at 3.7x/3.5x versus peer averages of 5.0x/4.8x, representing discounts of 26%/27%. This partly reflects AIIR’s lower 2027E EBITDA margin of 35.5% versus the 41.8% peer average. However, AIIR’s projected 2027 revenue and EBITDA growth of 5.0% and 8.0%, respectively, compares favorably with peer-average growth of approximately 3.4% and 5.2%. While AIIR’s smaller scale, regulatory exposure and NGC execution risks justify some discount, sustained earnings growth, margin recovery and improving cash conversion provide a basis for narrowing the valuation gap.
- Earnings normalization, deleveraging and shareholder returns provide tangible rerating catalysts, with Crown Switch offering incremental growth optionality. The recovery in shipments, Crown Switch’s PMTA submission and formalization of shareholder returns mark important progress since the previous quarter, with cash-flow normalization and deleveraging remaining key catalysts for further rerating. Continued pricing actions and easing logistics costs should support margin expansion, while working-capital normalization could restore cash conversion toward historical levels and support deleveraging to 2.0x or below by December 2027. The planned $0.28 annual dividend, representing an indicated yield of 3.6%, and up to $100 million in repurchases introduce a meaningful shareholder-return component to the investment case. Successful Crown Switch commercialization offers further upside beyond the core earnings framework. Overall, AIIR’s 9.9x 2027E EBITDA valuation offers exposure to a market-leading, cash-generative franchise with improving growth and margin prospects, while sustained cost inflation and delayed cash conversion remain key risks.
Read Exec Edge’s Initiation on AIR Global PLC Here
Subscribe to our Weekly Newsletter to Receive All Research
Contact: