Download the Complete Report Here
 Cherry Hill Mortgage Investment Corp. (CHMI)
Resilient Earnings and Dividend Coverage Support Outlook; MITT Merger Offers Long-Term Upside
- Key Takeaways:
- Underlying earnings resilience continues to support CHMI’s dividend, with EAD of $0.14/share providing 1.4x coverage and nine-month EAD growth of 34% y/y.
- Improved RMBS carry remains a key earnings driver, with NII rising 37% y/y and portfolio spreads holding at 3.45%.
- The MSR portfolio continues to provide earnings stability despite runoff, with servicing income rising 2% q/q to $7.5 million.
- Book-value volatility remains the principal counterweight to earnings strength, with BVPS declining 13.6% q/q despite substantial hedging gains.
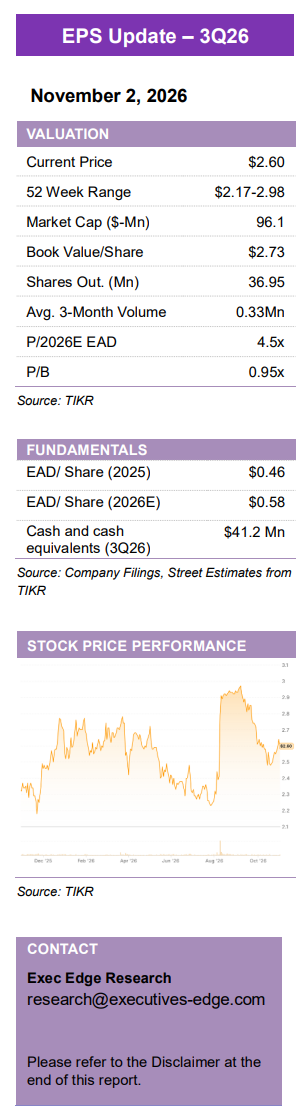
- CHMI trades at 4.5x 2026E EAD with a 15.4% dividend yield, while the MITT merger anchors near-term valuation and offers longer-term upside potential.
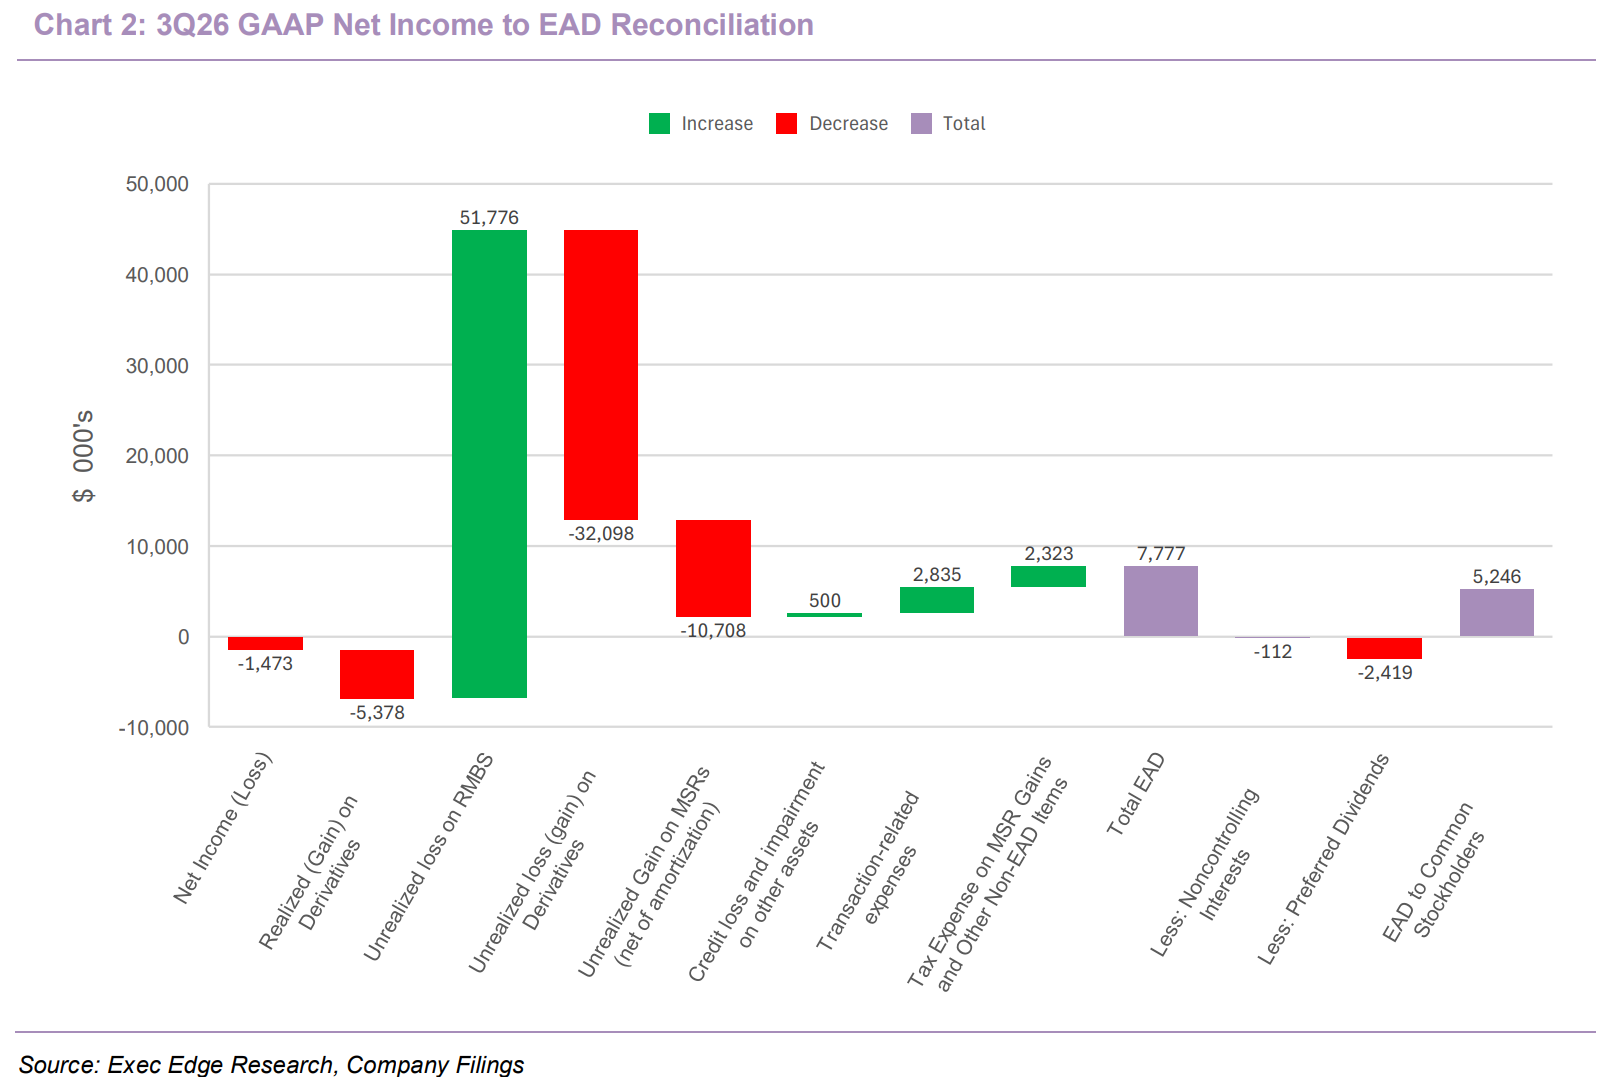
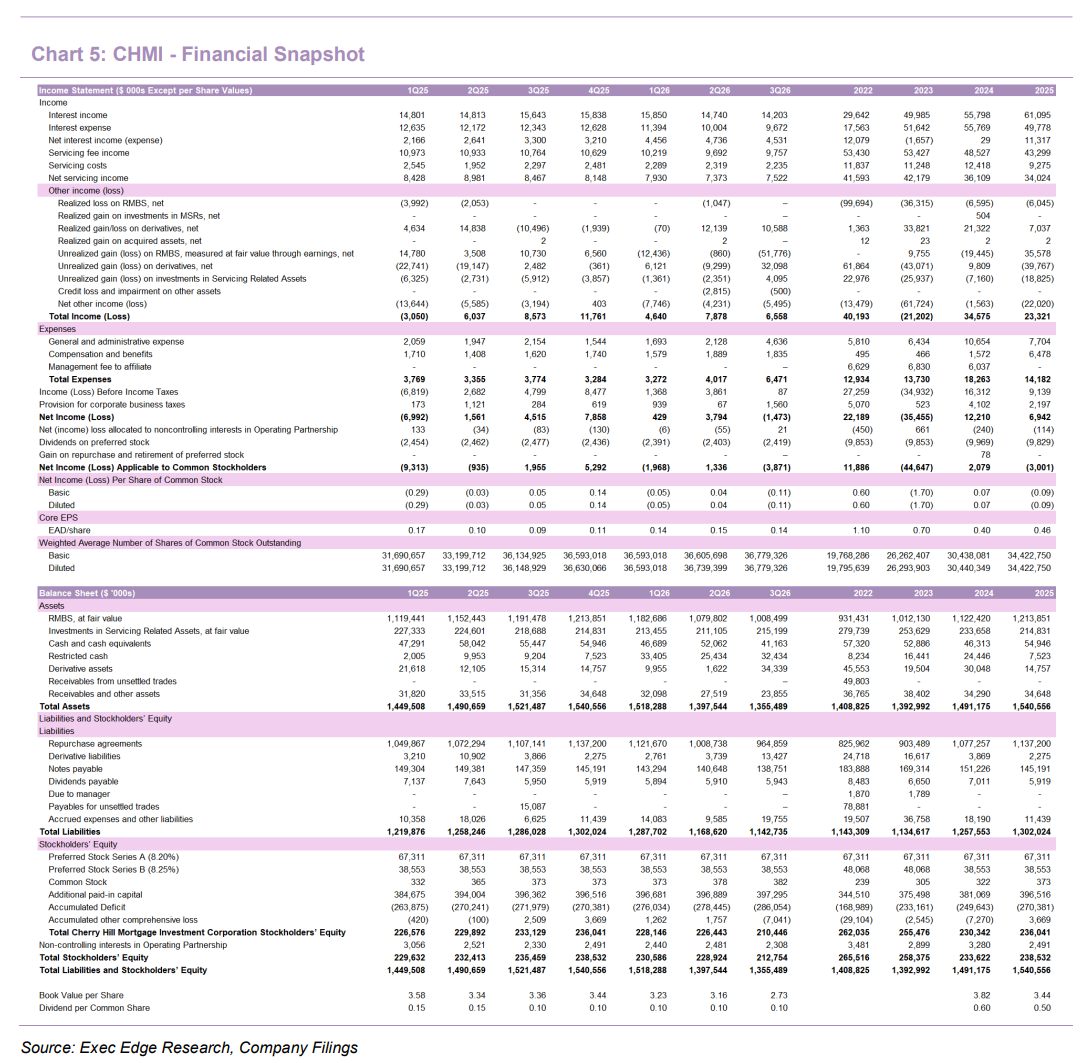
- Core earnings remained relatively stable, supporting dividend coverage despite modest sequential EAD moderation. CHMI reported earnings available for distribution (EAD) attributable to common stockholders of $5.2 million, or $0.14/share, in 3Q26 compared with $5.5 million, or $0.15/share, in 2Q26. The modest sequential decline was primarily driven by changes in price premium amortization, while underlying portfolio earnings and servicing cash flows remained relatively stable. Importantly, EAD for the first nine months of 2026 increased 34.4% y/y to $16.0 million from $11.9 million, or $0.44/share versus $0.35/share, reflecting meaningful improvement in underlying earnings generation. The $0.10/share quarterly dividend remained well covered at approximately 1.4x, compared with 1.5x in 2Q26, supporting the sustainability of the current payout despite continued mortgage portfolio volatility.
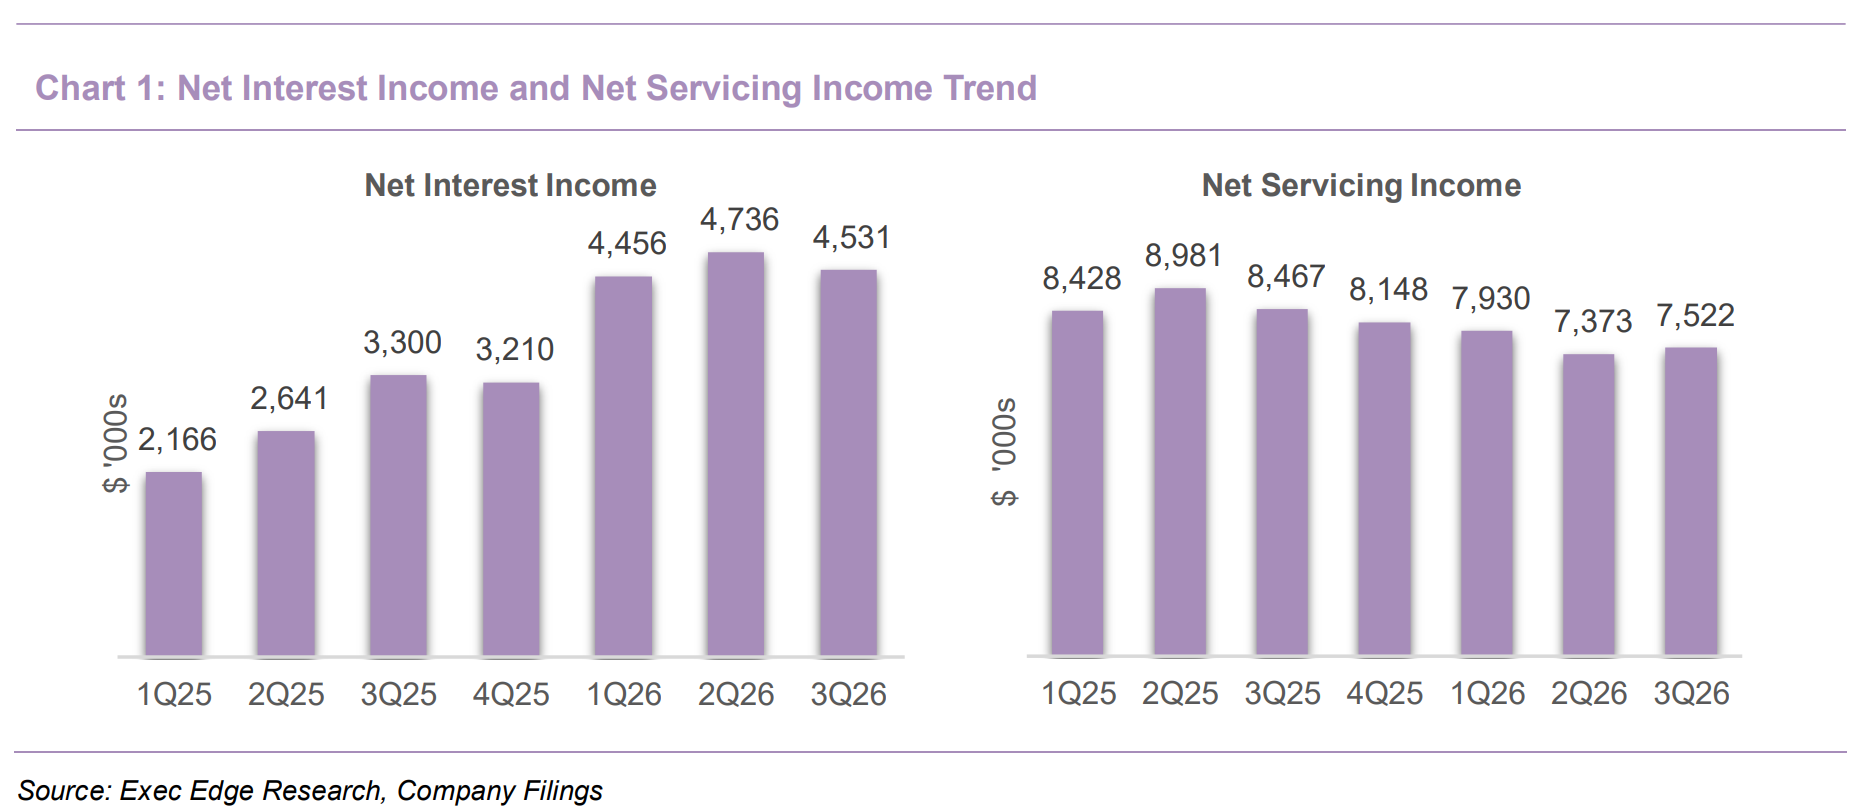
- Net interest income remained well above prior-year levels, although a smaller portfolio and changing financing economics moderated sequential performance. NII totaled $4.5 million in 3Q26 compared with $4.7 million in 2Q26 and $3.3 million in 3Q25, representing an increase of approximately 37% y/y. Interest income was $14.2 million versus $14.7 million sequentially, reflecting the smaller investment portfolio, while interest expense declined to $9.7 million from $10.0 million as financing balances decreased. On a year-over-year basis, interest expense declined 21.6% from $12.3 million, more than offsetting a 9.2% decline in interest income. For the first nine months of 2026, NII increased 69.3% to $13.7 million from $8.1 million in the prior year, supported by a $6.1 million reduction in financing expense. While lower outstanding borrowings supported NII, the quarter-end repo rate increased to 3.98% from approximately 3.76% in 2Q26, suggesting that further funding-cost benefits may be more limited.
Source: Exec Edge Research, Company Filings
- RMBS carry remained favorable despite significant portfolio valuation pressure, highlighting the divergence between recurring income and book value performance. The RMBS net interest spread held at 3.45% in 3Q26, unchanged sequentially and significantly above 2.52% at year-end 2025. The weighted-average asset yield used in the spread calculation increased to 5.80% from 5.24% at December 31, while weighted-average interest expense, including the benefit of related swaps, declined to 2.35% from 2.72%. This represents a 93-bps improvement in net interest spread over the first nine months of 2026 and highlights the underlying improvement in portfolio carry despite volatility in mortgage valuations. The RMBS portfolio ended September with approximately $1.0 billion in carrying value, a weighted-average coupon of 5.08% and a portfolio yield of 5.17%, compared with a 4.98% coupon and 5.08% yield at year-end 2025.
- Book value erosion highlights the divergence between recurring earnings and economic returns amid significant mortgage portfolio volatility. CHMI’s BVPS declined 13.6% q/q to $2.73 from $3.16 at June-end, compared with a 2.2% decline in 2Q26. Including the $0.10 quarterly dividend, total economic return was negative 10.4%, reversing the positive 0.9% return recorded in the prior quarter. GAAP net loss applicable to common stockholders totaled $3.9 million, or $0.11/share, compared with net income of $1.3 million, or $0.04/share, in 2Q26, primarily reflecting substantial RMBS mark-to-market losses, partially offset by derivative and servicing-related asset gains. Comprehensive loss attributable to common shareholders reached $12.7 million compared with comprehensive income of $1.8 million sequentially. In our view, stabilizing book value is increasingly important to CHMI’s investment case, particularly as favorable RMBS carry has not translated into positive economic returns.
- Hedging provided substantial protection against RMBS valuation losses, but residual mortgage basis exposure continued to pressure book value. CHMI recorded $32.1 million of unrealized derivative gains in 3Q26 versus a $9.3 million loss in 2Q26, a favorable $41.4 million swing. Realized derivative gains added $10.6 million versus $12.1 million sequentially, bringing total derivative gains to $42.7 million. These gains partially offset $51.8 million of unrealized RMBS losses through earnings and $8.9 million through other comprehensive income, highlighting the limitations of interest-rate hedging in fully offsetting mortgage asset valuation movements. At September-end, CHMI held $767.3 million in interest rate swaps, $415.4 million in net short TBA positions, $68.1 million in net short Treasury futures and $91.7 million in net short Eris SOFR swap futures. Net short TBA exposure increased from $266.9 million at June-end, reflecting active portfolio repositioning. The increased short TBA position also reflects a more defensive portfolio stance amid mortgage market volatility.
- MSR income remained stable despite portfolio runoff, providing a complementary source of earnings amid RMBS volatility. Net servicing income increased 2.0% q/q to $7.5 million from $7.4 million, supported by servicing fee income of $9.8 million versus $9.7 million and lower servicing costs of $2.2 million versus $2.3 million. However, net servicing income declined from $8.5 million in 3Q25, reflecting the gradual reduction in the underlying servicing portfolio. MSR unpaid principal balance decreased to approximately $14.9 billion from $15.2 billion sequentially and $15.9 billion at year-end 2025, representing a decline of approximately 6.5% YTD. The portfolio continues to benefit from a low 3.49% weighted-average mortgage coupon, limiting refinancing incentives and supporting servicing income durability. Recapture remained modest at 0.2% in 2Q26, the latest disclosed figure, limiting the offset to natural portfolio runoff. We believe the MSR portfolio remains an important source of earnings stability, although continued runoff limits its ability to support incremental income growth.
- Positive MSR valuation gains provided a partial offset to RMBS losses, although changing valuation assumptions remain important sensitivities. The company recognized a $4.1 million unrealized gain on investments in servicing-related assets compared with a $2.4 million unrealized loss in 2Q26, representing a positive sequential swing of approximately $6.4 million. The September 30 valuation incorporated a weighted-average assumed prepayment speed of 5.9%, compared with 6.5% at year-end 2025, and a discount rate of 10.4% versus 9.2%. The portfolio’s carrying value of $215.2 million remained relatively stable versus $214.8 million at December 31, even as underlying UPB declined from $15.9 billion to $14.9 billion. The relatively stable carrying value despite lower UPB underscores the contribution of valuation movements, although changes in prepayment and discount-rate assumptions remain important sensitivities.
- Merger-related costs drove higher operating expenses, while the Real Genius settlement provides greater clarity on the remaining investment exposure. Total operating expenses increased to $6.5 million in 3Q26 from $4 million in 2Q26, driven by G&A expense of $4.6 million versus $2.1 million sequentially. The increase largely reflected $2.8 million of transaction-related expenses incurred in connection with the pending MITT merger, which were excluded from EAD, compared with $0.2 million in the prior quarter. Compensation and benefits remained relatively stable at $1.8 million versus $1.9 million. Separately, CHMI recorded an additional $0.5 million provision for credit losses on the promissory note associated with Real Genius, bringing the cumulative allowance to $2.8 million against the original $3.2 million principal balance. Subsequent to quarter-end, on October 21, CHMI entered into a discounted payoff agreement under which it will accept $0.4 million as full settlement of the note, receiving approximately $0.3 million on October 22, with the remainder payable over three years. The settlement provides a defined recovery path for the remaining Real Genius exposure, while merger-related expenses remain a near-term consideration as CHMI progresses toward the MITT transaction closing.
- Portfolio cash generation improved, but higher collateral requirements reduced available liquidity. Operating cash flow increased to $17.0 million in 3Q26 from $4.6 million in 2Q26, bringing nine-month operating cash generation to $34.3 million versus $10.7 million y/y. Investing activities generated $30.7 million during the quarter, reflecting RMBS principal repayments, portfolio sales and derivative settlements. At September-end, unrestricted cash declined 20.9% q/q to $41.2 million from $52.1 million, while restricted cash increased to $32.4 million from $25.4 million. The higher restricted cash balance, including $15.7 million pledged against derivatives and $16.7 million against repo financing, highlights the role of collateral requirements in CHMI’s liquidity position.
- CHMI’s diversified funding structure provides flexibility to navigate mortgage market volatility ahead of the MITT merger. Aggregate portfolio leverage increased to 5.19x from 5.02x in 2Q26, while repo borrowings declined to $964.9 million from $1.01 billion sequentially and $1.14 billion at year-end 2025. Financing remained diversified across 18 repo counterparties, with a weighted-average haircut of 4.4% and no individual counterparty exposure exceeding 5% of stockholders’ equity. CHMI also maintained $200 million in committed MSR financing capacity through its Freddie Mac and Fannie Mae facilities, with approximately $139 million outstanding at September-end. The combination of lower absolute borrowings and established financing relationships provides funding flexibility, although higher leverage and short-term repo exposure remain important monitorables amid mortgage market volatility.
- Healthy dividend coverage supports shareholder distributions, while capital allocation remains focused on preserving flexibility ahead of the MITT merger. The company maintained its quarterly common dividend at $0.10/share, equivalent to an annualized payout of $0.40/share and a dividend yield of 15.4%. The dividend was covered approximately 1.4x by 3Q26 EAD, while nine-month EAD of $0.44/share covered cumulative common dividends of $0.30/share by approximately 1.5x. Preferred dividends also continued as scheduled, with Series A and Series B dividends of $0.5125 and $0.6162/share, respectively, paid in October. Capital allocation remained conservative, with no ATM issuance or common or preferred share repurchases during the first nine months of 2026. With book value declining 13.6% sequentially and unrestricted cash at $41.2 million, maintaining liquidity and dividend coverage remains a priority ahead of the proposed combination.
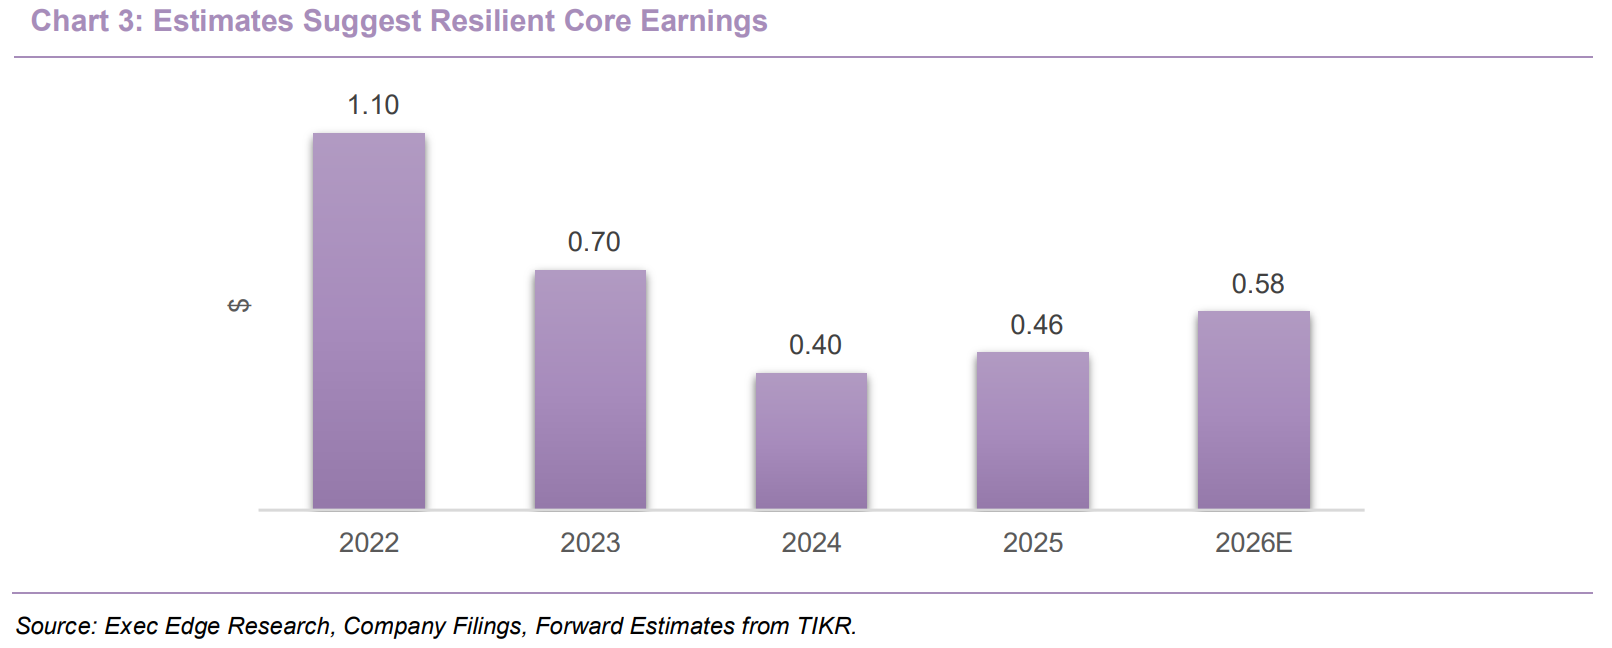
- Full-year earnings expectations remain supportive despite sequential EAD moderation, with favorable portfolio carry underpinning the outlook. Street estimates sourced from TIKR indicate 2026E EAD of $0.58/share, compared with $0.46/share in 2025 and $0.40/share in 2024. With EAD of $0.44/share generated during the first nine months of 2026, current estimates imply a relatively stable underlying earnings run rate through year-end, although the smaller RMBS portfolio and servicing runoff remain offsets. The expected improvement is supported by the expansion in RMBS net interest spread to 3.45%, improved financing economics relative to 2025 and recurring servicing cash flows. We believe the 2026E earnings outlook supports the current dividend, although improved book-value stability will be important for translating recurring earnings into stronger shareholder returns.
Covered Earnings and MITT Merger Support Valuation Upside
- Disclaimer: Exec Edge does not publish proprietary estimates, ratings, price targets, or investment recommendations. The valuation discussion below is illustrative only and is based on company filings, management commentary, and third-party data and estimates. It does not constitute a recommendation, price target, rating, or prediction of future pricing.
- The pending MITT merger is expected to create a $9.0 billion residential mortgage investment platform in 4Q26, offering CHMI shareholders greater scale and operating efficiencies. Under the agreement announced on August 10, 2026, CHMI shareholders will receive 0.3063 MITT shares and $0.93 in cash per share, representing an initial transaction value of approximately $3.10/share and a 29% premium to CHMI’s unaffected August 7 closing price. CHMI shareholders are expected to own approximately 27% of the combined company, with management targeting $7 million to $9 million in annual operating efficiencies. TPG’s mortgage origination, acquisition and asset management capabilities could also support MSR portfolio growth and more efficient capital deployment. The transaction remains subject to shareholder approvals, with meetings scheduled for December 2, 2026, and closing targeted for 4Q26. We believe the combination addresses CHMI’s relatively small operating scale, with successful integration and realization of expected efficiencies important to the longer-term investment case.
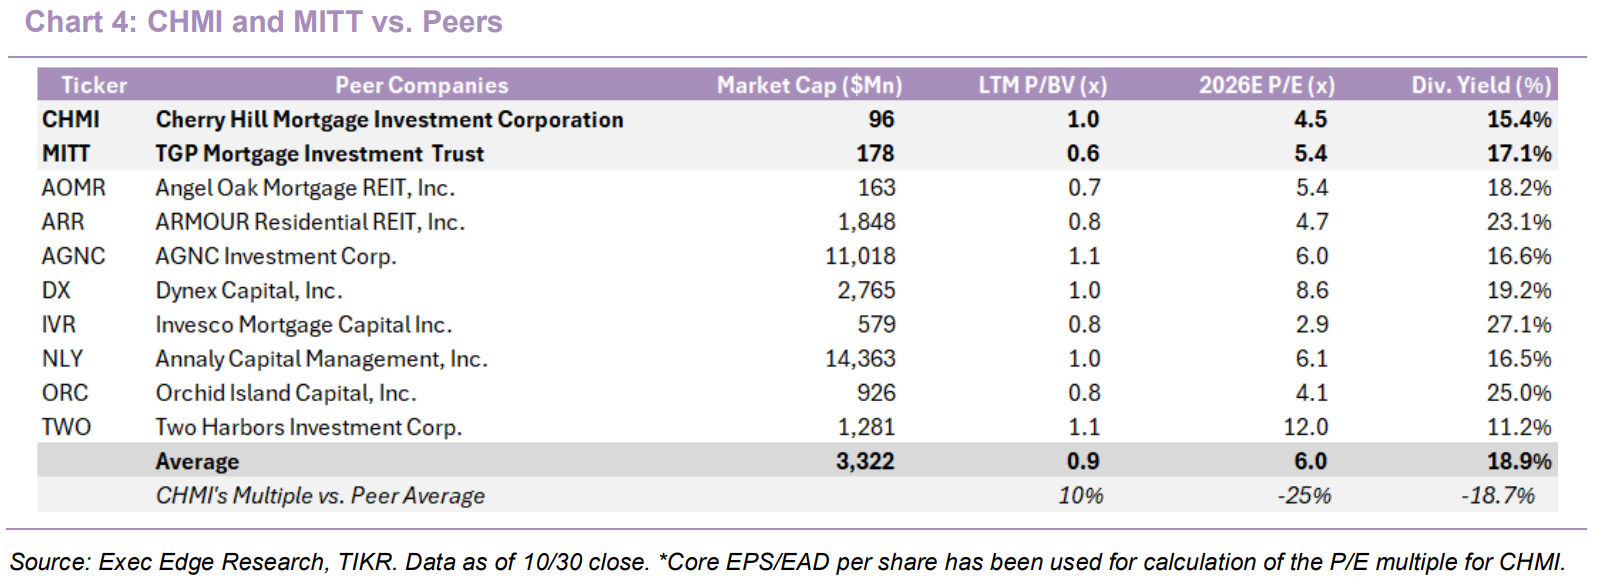
- CHMI’s attractive earnings yield and covered dividend support its valuation, while the MITT transaction provides a clear near-term pricing reference. At the October 30 closing price of $2.60, CHMI has a market capitalization of approximately $96 million and trades at 4.5x Street 2026E EAD of $0.58/share, with a dividend yield of 15.4%. The stock trades at 0.95x September-end BVPS of $2.73, compared with 0.82x June-end book value of $3.16 at the same share price, reflecting the impact of the 13.6% sequential book-value decline. At MITT’s October 30 closing price of $5.60, the agreed consideration implies approximately $2.65 per CHMI share, or a 1.7% premium to CHMI’s closing price, compared with $3.10/share at announcement. We believe CHMI’s recurring earnings remain supportive of its current valuation, while the fixed exchange ratio makes MITT’s share-price performance and successful transaction completion the primary near-term valuation drivers.
- MITT’s discount to peers provides potential longer-term valuation upside, supported by operating synergies and opportunities for improved earnings and book-value performance. At the October 30 closing price of $5.60, MITT has a market capitalization of ~$178 million and trades at 0.6x book value and 5.4x 2026E earnings, compared with mortgage REIT peer benchmarks of 0.9x and 6.0x, respectively. Its 17.1% dividend yield compares with CHMI’s 15.4% indicated yield, supporting the combined investment’s income appeal. With ~65% of the implied consideration represented by MITT shares, CHMI shareholders retain exposure to any improvement in MITT’s valuation. In our view, a more favorable interest-rate environment, combined with expected merger efficiencies, could support earnings growth and book-value stability, strengthening the case for a narrowing of MITT’s valuation discount to peers. Successful transaction completion remains the immediate catalyst, while sustained earnings, book-value stability and realization of merger efficiencies will determine the scope for longer-term valuation improvement.
Read Exec Edge’s Initiation on Cherry Hill Here
Subscribe to our Weekly Newsletter to Receive All Research
Contact: