
Download the Complete Report Here
 The ONE Group Hospitality, Inc. (STKS)
Positive Traffic, Expanding Restaurant Margins and Stronger Free Cash Flow Reinforce Operating Recovery; Benihana Express Accelerates Asset-Light Growth.
- Key Takeaways
- Consolidated transactions increased 1.8%, signaling improving underlying demand, despite a 0.4% comparable-sales decline and 1.8% lower reported revenue from planned Grill closures.
- Procurement efficiencies reduced restaurant cost of sales 160 bps to 19.5%, driving 190 bps of restaurant operating margin expansion to 13.2%.
- Year-to-date operating cash flow increased 143% to $41.8 million, generating $7.2 million of free cash flow after $34.6 million in gross capex.
- Benihana Express Miami now paces at $1.8 million in annualized sales, reinforcing licensing potential as STKS advances seven remaining Grill conversions.
- Valuation remains attractive given improving operating fundamentals, stronger cash conversion and capital-efficient growth opportunities.
- Positive traffic trends continued to signal an underlying demand recovery, although cautious consumer spending and planned portfolio closures constrained reported revenue growth. STKS reported 3Q26 revenue of $177.0 million, down 1.8% y/y but within management’s $176-$180 million guidance range. The decline primarily reflected $4.5 million of lost revenue from Grill Concepts closures, partly offset by new openings and conversions. Consolidated comparable sales declined 0.4%, versus 0.9% growth in 2Q26 and guidance of 0-2% growth, but improved materially from the 5.9% decline in 3Q25. Comparable transactions increased 1.8%, marking the second consecutive quarter of positive traffic and third consecutive quarter of sequential improvement. Sales were trending positively through Labor Day before adverse East Coast weather disrupted September performance. Positive transaction growth underscores the effectiveness of traffic-driving initiatives, although value-oriented spending continues to weigh on average checks and comparable sales.
- Benihana continues to anchor the operating recovery, while positive traffic at STK and Grill Concepts signals broader stabilization. Benihana comparable sales increased 0.7% in 3Q26, following 0.8% growth in 2Q26 and improving from a 4.0% decline in 3Q25. Comparable transactions rose 2.7%, supported by value-oriented weekday offerings and premium celebration dining. U.S. STK comparable sales declined 0.9%, versus 3.2% growth in 2Q26 and a 5.8% decline in 3Q25, with company-owned locations down 1.2% and managed locations up 0.3%. Grill Concepts comparable sales declined 4.0%, versus declines of 2.9% in 2Q26 and 11.8% in 3Q25, although transactions increased 1.7% during the quarter and 1.4% YTD, indicating improving customer engagement despite continued sales pressure.
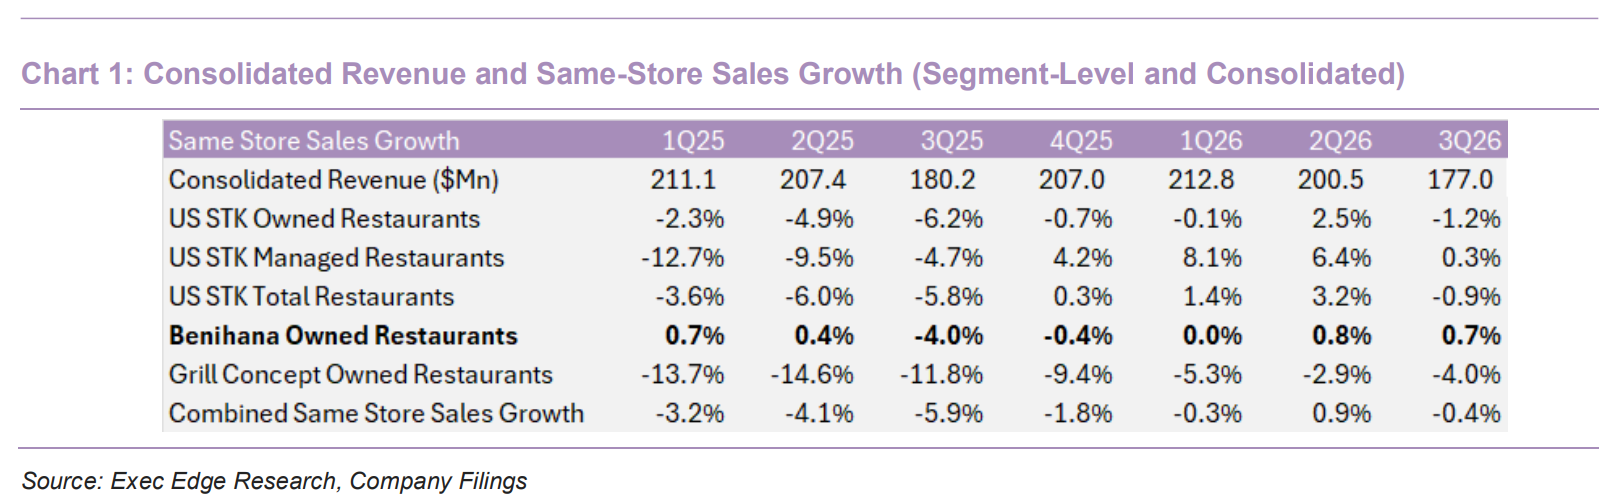
- Planned Grill closures continue to weigh on reported revenue, masking improving underlying demand and the benefits of portfolio optimization. Through 9M26, consolidated revenue declined 1.4% to $590.3 million, while company-owned restaurant revenue fell 1.3% to $580.9 million. The decline included ~$20.0 million of lost revenue from Grill Concepts closures and $3.1 million from eliminating automatic gratuities, which had no earnings impact. These headwinds were partly offset by $8.3 million from the fiscal calendar shift and $6.9 million from new openings and comparable sales changes. Consolidated comparable sales increased 0.1% YTD, improving from a 3.7% decline in 9M25, reinforcing the distinction between reported revenue pressure and improving underlying restaurant demand.
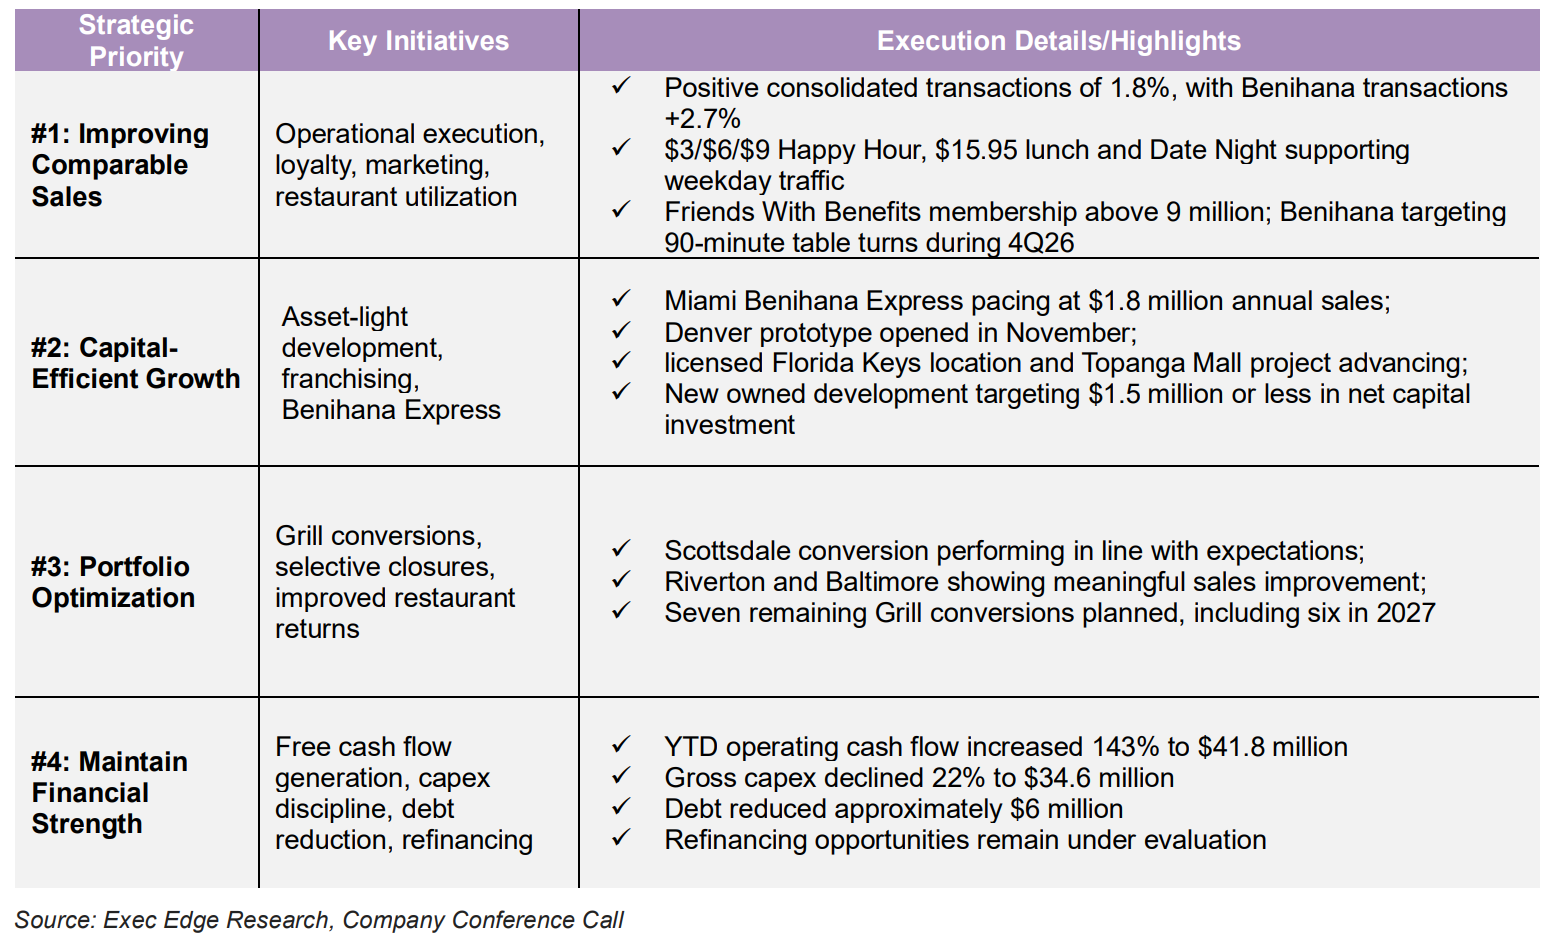
- STKS’ barbell strategy is driving customer traffic by combining accessible weekday offerings with premium dining experiences across weekends, holidays and celebrations. The company’s $3, $6 and $9 Happy Hour, Weeknight Date Night promotions and Benihana’s $15.95 weekday lunch with a 45-minute service guarantee are attracting value-conscious customers during traditionally slower periods. These initiatives complement premium offerings such as steaks, Wagyu, seafood and specialty cocktails, broadening dining occasions without compromising premium positioning. The strategy is gaining traction, with consolidated comparable transactions increasing 1.8% in 3Q26 despite a 0.4% decline in comparable sales. Benihana’s 2.7% transaction growth and 0.7% comparable-sales increase further demonstrate the strategy’s effectiveness.
- Loyalty engagement and menu innovation are reinforcing traffic gains by encouraging repeat visits and strengthening customer retention. STKS’ Friends With Benefits loyalty program has surpassed 9 million members, with approximately 1 million organic additions expected in 2026. Loyalty members spend more per visit and dine more frequently, providing a foundation for targeted promotions and personalized engagement. Seasonal menu refreshes, undertaken at least four times annually, further sustain customer interest, with recent additions including cauliflower fried rice at Benihana and premium non-alcoholic cocktails at STK. Together, these initiatives support restaurant utilization, repeat spending and customer lifetime value.
- STKS is improving capital efficiency through higher restaurant utilization and lower-cost development, with Benihana Express emerging as a scalable growth platform. Off-premise dining, representing approximately 10% of YTD sales, provides additional revenue opportunities, while Benihana’s targeted reduction in table-turn times from approximately 105 minutes during the 2025 holiday season to 90 minutes in 4Q26 should increase peak-period capacity, with the anticipated benefit already reflected in management’s outlook. Expanded weekend brunch at STK and Kona Grill further supports utilization during underpenetrated dayparts. STKS continues prioritizing development projects requiring approximately $1.5 million or less in net investment, supported by landlord contributions and existing infrastructure. Recent openings and conversions include STK Chelsea, Benihana Riverton and STK Baltimore, with the 2026 development target narrowed to six to eight venues. Benihana Express’s Miami prototype now generates approximately $1.8 million in annualized sales, up 50% from its prior pace. The 800-1,000-square-foot format, with estimated development costs of $400-500 per square foot, offers a scalable, lower-capital alternative to full-service development, with management prioritizing Express over other new licensing initiatives.
- Grill portfolio optimization offers a meaningful margin improvement opportunity, with seven remaining conversions expected to enhance returns from existing restaurant real estate through 2027. STKS currently operates 20 Kona Grill and 12 RA Sushi locations, including temporary closures, with four Kona Grills and three RA Sushi restaurants earmarked for Benihana conversions. Net conversion costs are estimated at $1.0-1.5 million per location, with relatively short anticipated payback periods. One conversion is expected to reopen by year-end 2026, followed by six during 2027. STKS has also exited three underperforming Grill locations following lease expirations. The strategy addresses a meaningful profitability gap, with core Grill Concepts restaurant operating margin declining to 3.0% in 3Q26 from 4.0% a year earlier, while YTD margin fell to 4.8% from 8.2%.
- Early conversion results support the portfolio optimization strategy, with stronger sales and improving unit economics demonstrating the potential to increase returns on existing real estate. The Scottsdale RA Sushi-to-STK conversion is delivering sales and profitability consistent with expectations while materially outperforming its predecessor. The Riverton, Utah, Benihana conversion has generated a meaningful sales increase over the former Kona Grill, while Baltimore’s redevelopment into an STK and smaller Kona Grill has approximately doubled combined sales versus the previous restaurant. While profitability at the newer conversions remains to be established, successful execution of the remaining pipeline should shift the portfolio toward higher-productivity restaurants, improving operating margins and reducing the earnings drag from underperforming Grill locations.
- STKS continues to advance its four strategic priorities, with improving restaurant performance, portfolio optimization and capital-efficient development supporting stronger cash generation and long-term profitability. The company’s performance reflects progress across these initiatives, including 1.8% consolidated transaction growth in 3Q26, a 190-bp improvement in restaurant operating margin and $41.8 million of YTD operating cash flow. The emphasis is increasingly on maximizing returns from existing assets and disciplined capital deployment rather than capital-intensive revenue growth.
- Procurement synergies and operating efficiencies continue to drive restaurant-level margin expansion, reinforcing the earnings benefits of the Benihana acquisition despite softer revenue. Company-owned restaurant cost of sales improved 160 bps to 19.5% in 3Q26, sustaining the improvement achieved over the past three quarters. Operating expenses excluding cost of sales declined 30 bps to 67.3%, lifting restaurant operating profit 14.7% y/y to $23.1 million and expanding margin 190 bps to 13.2%. YTD operating profit increased 9.6% to $95.2 million, with margin improving 160 bps to 16.4%. Benihana remained the principal earnings contributor, generating approximately 70% of consolidated restaurant operating profit as its margin expanded 190 bps to 15.8%. STK also improved profitability, with restaurant operating profit rising to $6.2 million from $5.9 million and margin expanding 40 bps to 13.2%. These gains reflect purchasing scale, favorable beef sourcing, menu optimization and operating efficiencies, with procurement agreements providing additional cost visibility into 2027. The sustained improvement also strengthens the economics of converting underperforming Grill restaurants into higher-margin brands.
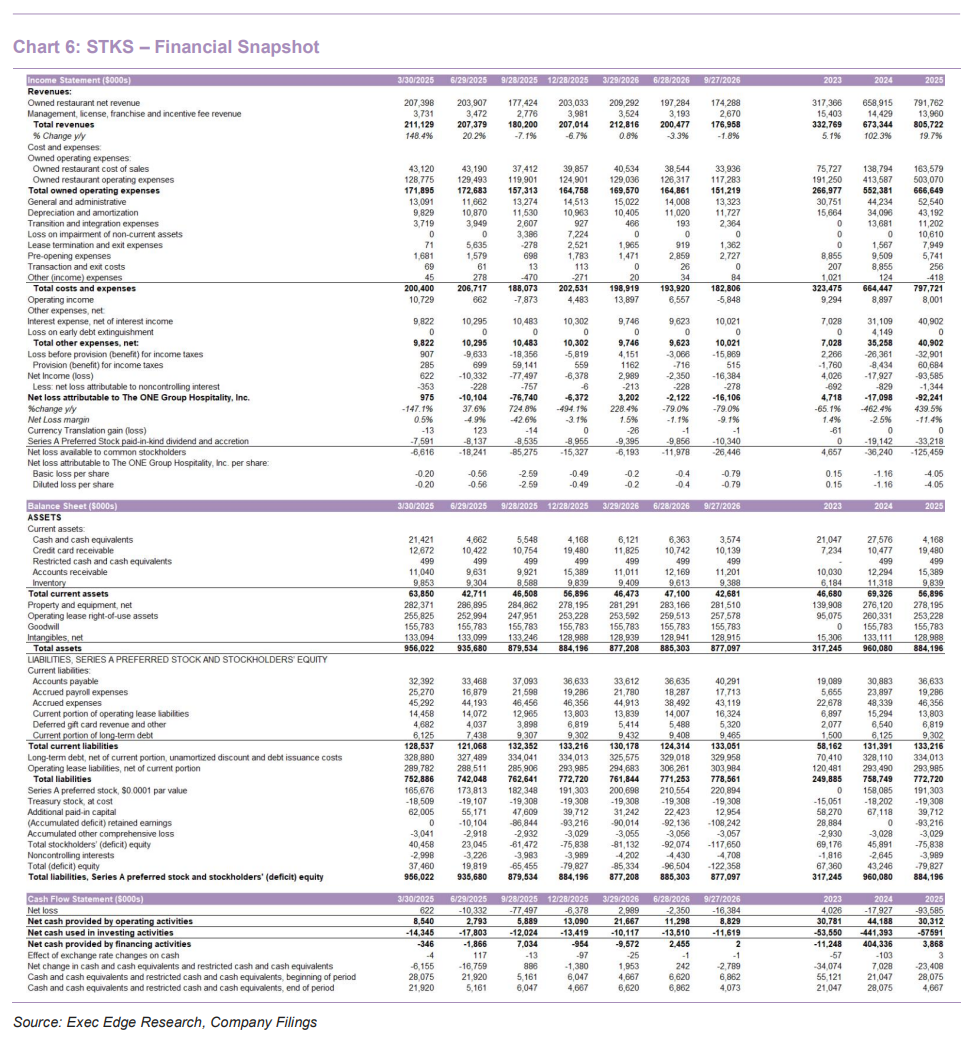
- Adjusted EBITDA returned to growth as stronger restaurant profitability and declining integration expenses supported improved earnings conversion, although results fell short of guidance. Adjusted EBITDA attributable to STKS increased 5.4% y/y to $11.1 million, below the $12-$15 million guidance range, while margin expanded 40 bps to 6.3%. GAAP operating loss narrowed to $5.8 million from $7.9 million, although pre-opening expenses increased to $2.7 million from $0.7 million, exceeding management’s $1-$2 million guidance range. G&A remained stable at $13.3 million, while YTD integration expenses declined to $3.0 million from $10.3 million, with no further significant costs anticipated. Consequently, YTD GAAP operating income increased to $14.6 million from $3.5 million, while adjusted EBITDA rose to $60.8 million from $59.1 million. Net loss attributable to STKS narrowed to $16.1 million from $76.7 million, with diluted EPS improving to ($0.79) from a restated ($2.59), although the prior-year result included a $59.1 million noncash tax valuation allowance, limiting the usefulness of the GAAP comparison.
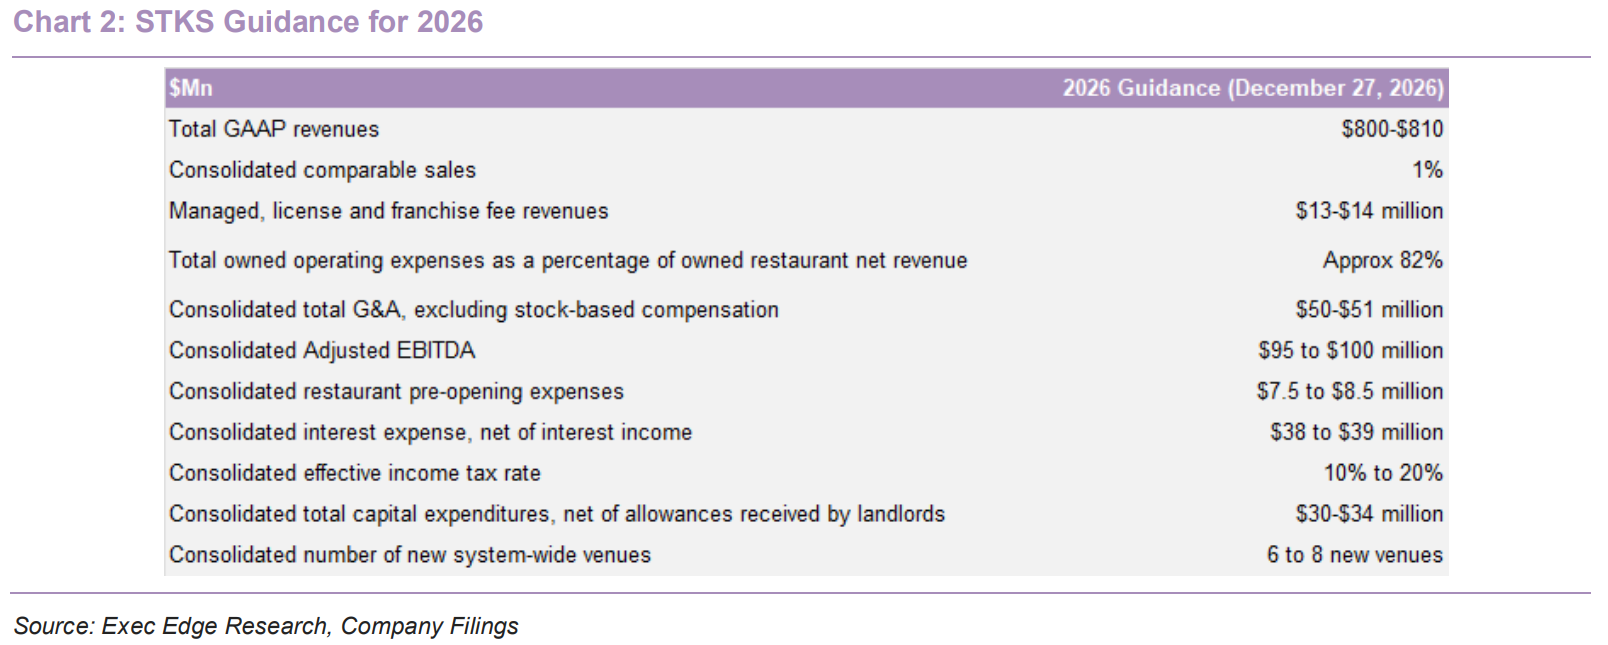
- STKS’ revised 2026 outlook preserves the margin recovery thesis, but lower revenue expectations and a narrower EBITDA range place greater emphasis on fourth-quarter execution. Management lowered revenue guidance to $800-810 million from $805-820 million, reflecting approximately 1% comparable-sales growth, while adjusted EBITDA guidance narrowed to $95-100 million from $95-105 million. Restaurant operating expenses are expected to represent approximately 82% of company-owned revenue, implying an 18% restaurant operating margin. Net capital expenditures remain targeted at $30-34 million, alongside six to eight system-wide openings. Based on YTD results, the outlook implies 4Q26 revenue of approximately $210-220 million and adjusted EBITDA of $34-39 million. Robust holiday bookings, STK event reservations tracking above prior-year levels and targeted Benihana throughput improvements provide support for the seasonal earnings recovery, although the implied fourth-quarter EBITDA contribution remains substantial.
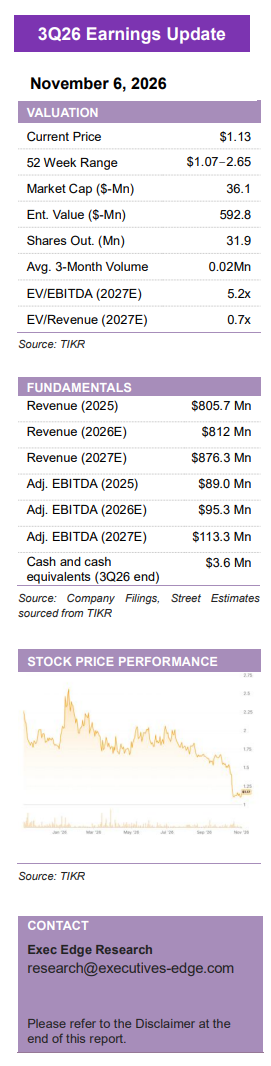
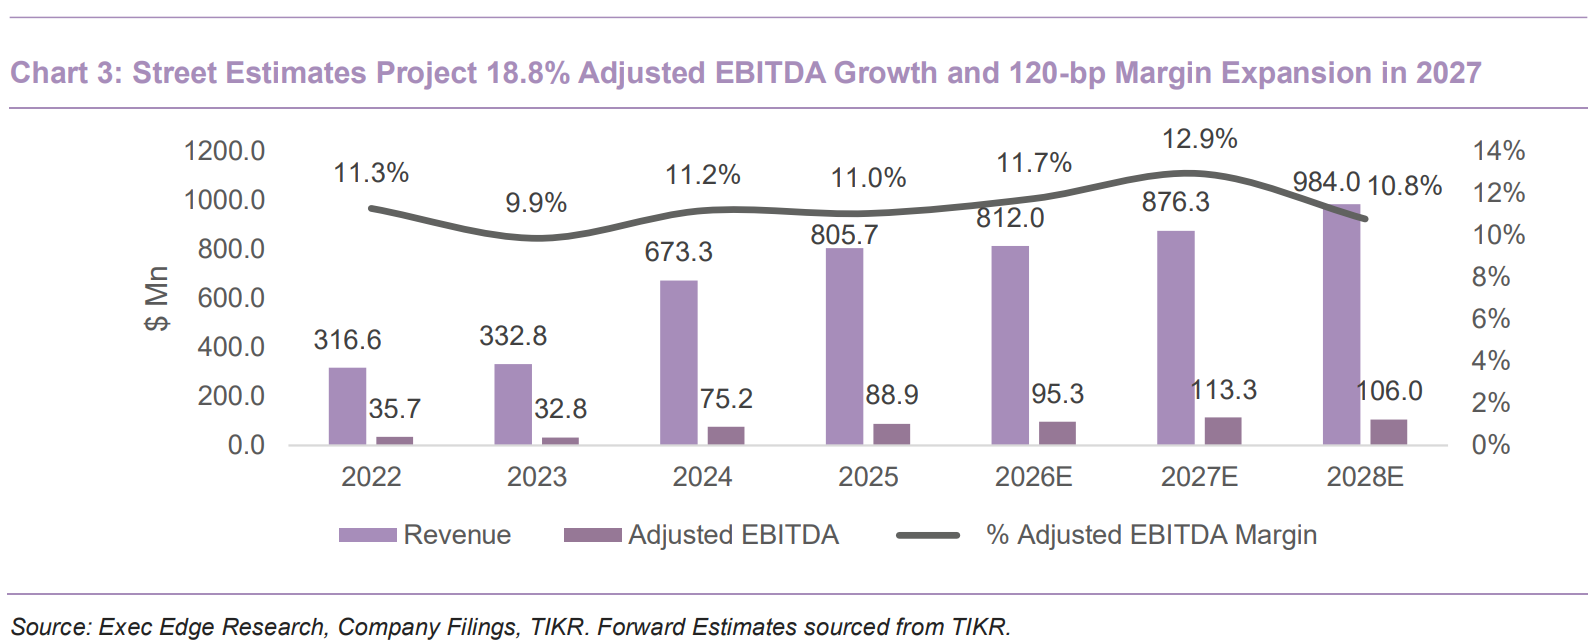
- Street estimates anticipate accelerating revenue growth and stronger operating leverage in 2027, supported by portfolio conversions, improving restaurant productivity and capital-efficient expansion. Street estimates sourced from TIKR indicate revenue of $812.0 million in 2026, slightly above management’s updated guidance, increasing 7.9% to $876.3 million in 2027 and 12.3% to $984.0 million in 2028. Adjusted EBITDA is expected to increase from $95.3 million in 2026 to $113.3 million in 2027, with margins expanding from 11.7% to 12.9%. GAAP EPS is expected to improve from a loss of $1.16 in 2026 to losses of $0.38 in 2027 and $0.04 in 2028. With 2026 consensus revenue and EBITDA estimates already revised lower, sustained margin improvement remains central to the longer-term earnings outlook.
- Stronger operating cash flow and lower capital intensity are improving cash conversion, creating greater capacity to fund growth and reduce debt. Operating cash flow increased 143% y/y to $41.8 million from $17.2 million, including a 50% increase to $8.8 million in 3Q26. Improved receivable collections contributed $13.5 million to YTD cash flow versus $2.1 million a year earlier, alongside higher restaurant operating profit and lower integration costs. Gross capital expenditures declined 22% to $34.6 million, while spending net of landlord allowances fell 31% to $28.3 million. Maintenance capex decreased 53% to $7.4 million, while new restaurant investment remained relatively stable at $23.3 million, indicating that capital discipline has not materially constrained development. Consequently, free cash flow after gross capex reached $7.2 million, while cash flow excluding new restaurant investment totaled approximately $30.5 million, or roughly 50% of adjusted EBITDA.
- Improving cash generation, modest deleveraging and lower borrowing costs are strengthening STKS’ financial flexibility. STKS ended 3Q26 with approximately $40 million in short-term liquidity, including $3.6 million in cash, $10.1 million in credit-card receivables and $26.2 million in available revolving capacity. Total debt declined $6.3 million YTD to $347.9 million, while the weighted-average interest rate improved to 10.2% from 10.7%, reducing quarterly net interest expense to $10.0 million from $10.5 million. The term loan and revolving facility mature in April 2029 and November 2028, respectively, providing time to pursue refinancing opportunities. However, Series A preferred equity increased to $220.9 million from $191.3 million at year-end 2025, reflecting $29.6 million in YTD paid-in-kind dividends and accretion. The preferred security carries a 13% compounding dividend rate, with a $247.4 million future redemption value reflected in 2027 accounting estimates rather than a mandatory repayment obligation. Preferred dividends and accretion reached $10.3 million in 3Q26, weighing on earnings available to common shareholders, while approximately 1.9 million penny warrants represent additional potential dilution. Reducing these financing claims remains critical to translating operating improvements into common-equity value.
- Capital allocation remains focused on deleveraging and selective restaurant development, with the renewed share repurchase authorization providing additional flexibility. STKS reduced debt by approximately $6.3 million during 9M26 while investing $23.3 million in new restaurant development, supported by stronger operating cash flow and a shift toward lower-cost conversions and asset-light expansion. Management’s 2026 net capex guidance of $30-34 million reinforces its emphasis on disciplined capital deployment. On November 3, the Board authorized an additional $5 million for common-share repurchases, following approximately 3.4 million shares previously repurchased for $19.3 million. No repurchases occurred during 9M26, underscoring the near-term priority given to operating requirements, development and debt reduction.
Improving Fundamentals and Cash Generation Support Re-Rating Potential
- Disclaimer: Exec Edge does not publish proprietary estimates, ratings, price targets, or investment recommendations. The valuation discussion below is illustrative only and is based on company filings, management commentary, and third-party data and estimates. It does not constitute a recommendation, price target, rating, or prediction of future pricing.
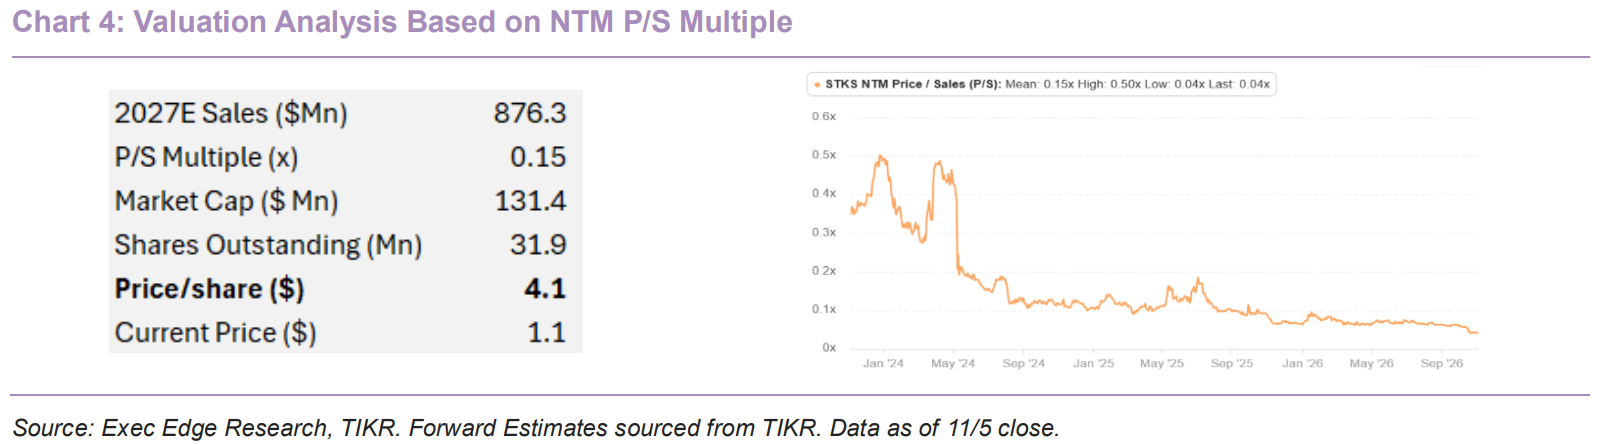
- STKS remains attractively valued as improving restaurant profitability, stronger cash generation and capital-efficient expansion support a sustained operating recovery. As of 11/5 close, STKS has a market capitalization of $36 million and trades at 0.04x 2027E P/S, substantially below its three-year historical mean of 0.15x. Applying this historical multiple to projected 2027 revenue of $876.3 million implies an illustrative equity valuation of $131.4 million, or $4.10 per share. We note that this is an illustrative valuation and should not be interpreted as a price target. The valuation discount appears increasingly disconnected from improving fundamentals, with 3Q26 comparable transactions growing 1.8%, restaurant operating margin expanding 190 bps and YTD operating cash flow increasing 143% to $41.8 million. These improvements, alongside lower capital requirements and portfolio optimization, provide a foundation for multiple normalization.
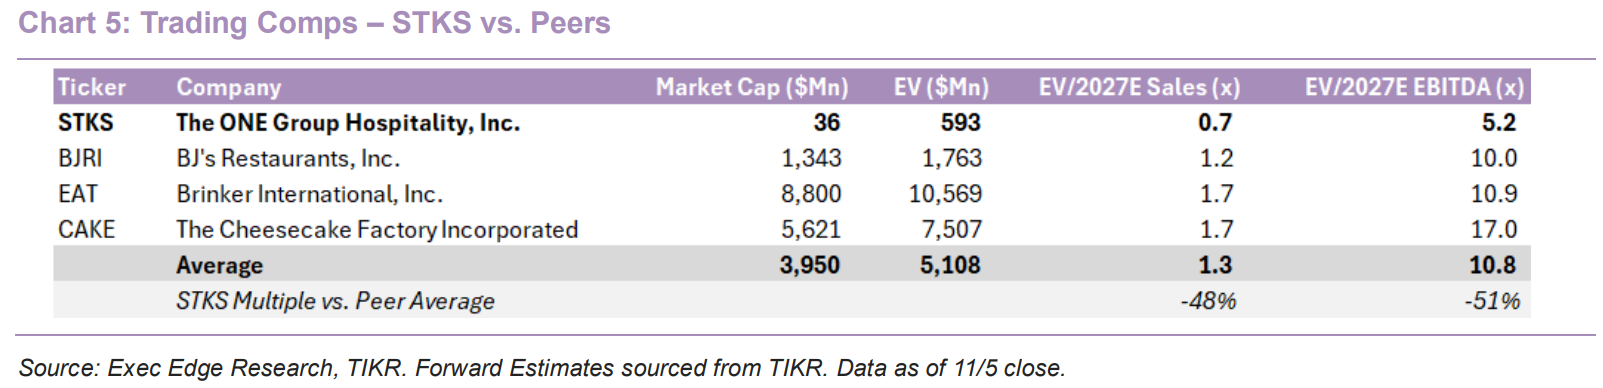
- Relative valuation reinforces STKS’ attractive positioning, with the company trading at a substantial discount to established full-service restaurant peers. With an enterprise value of approximately $593 million, STKS trades at 0.7x 2027E revenue and 5.2x 2027E adjusted EBITDA, compared with supplied peer averages of 1.3x revenue and 10.8x EBITDA, representing discounts of approximately 48% and 51%, respectively. The discount persists despite an improving earnings trajectory, with adjusted EBITDA projected to increase 18.8% to $113.3 million in 2027, supported by portfolio conversions, stronger restaurant productivity and operating leverage. Continued margin improvement and cash generation strengthen the case for narrowing the valuation gap as the portfolio transition progresses.
- Sustained operating momentum, capital-efficient growth and stronger free cash flow provide identifiable catalysts for a valuation re-rating. Management’s 2026 adjusted EBITDA guidance of $95 million to $100 million establishes a foundation for continued earnings growth, while portfolio optimization and Benihana Express expansion offer opportunities to improve restaurant productivity, capital returns and longer-term growth. Meanwhile, YTD free cash flow of $7.2 million, lower recurring capital requirements and continued debt reduction are improving financial flexibility. Together, recovering traffic, procurement-driven margin expansion and a more capital-efficient growth model support stronger cash conversion and potential multiple normalization, with sustained deleveraging remaining important to common-equity value creation.
Read Exec Edge’s Initiation on The ONE Group Here
Subscribe to our Weekly Newsletter to Receive All Research
Contact: