Download the Complete Report Here
Otovo ASA (OTOVO)
Field Services Momentum and Endurance Efficiencies Drive Profitability Inflection and Re-Rating Potential
- Key Takeaways:
- Field Services revenue grew 70% q/q to $5.6 million, while Newbuild declined 44%, lifting services to approximately two-thirds of consolidated revenue.
- October work orders reached 4,049, up 46% from August, with $760 revenue per order and 52% estimated gross margin, reinforcing improving service economics.
- Endurance-enabled efficiencies helped reduce adjusted opex 26% q/q to $5.6 million, driving OTOVO’s first positive monthly adjusted EBITDA in September.
- Expanding technician capacity and acquisition-led growth underpin management’s 2027 targets of $120 million revenue and $36 million adjusted EBITDA.
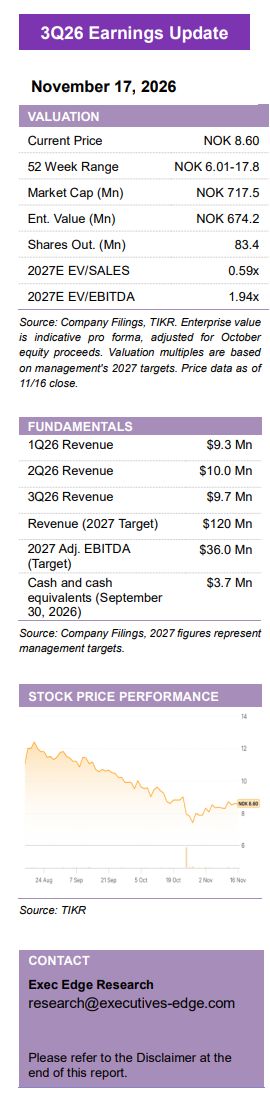
- At 0.59x targeted 2027 sales and 1.94x adjusted EBITDA, OTOVO trades at a substantial service-peer discount, offering re-rating potential as profitability scales.
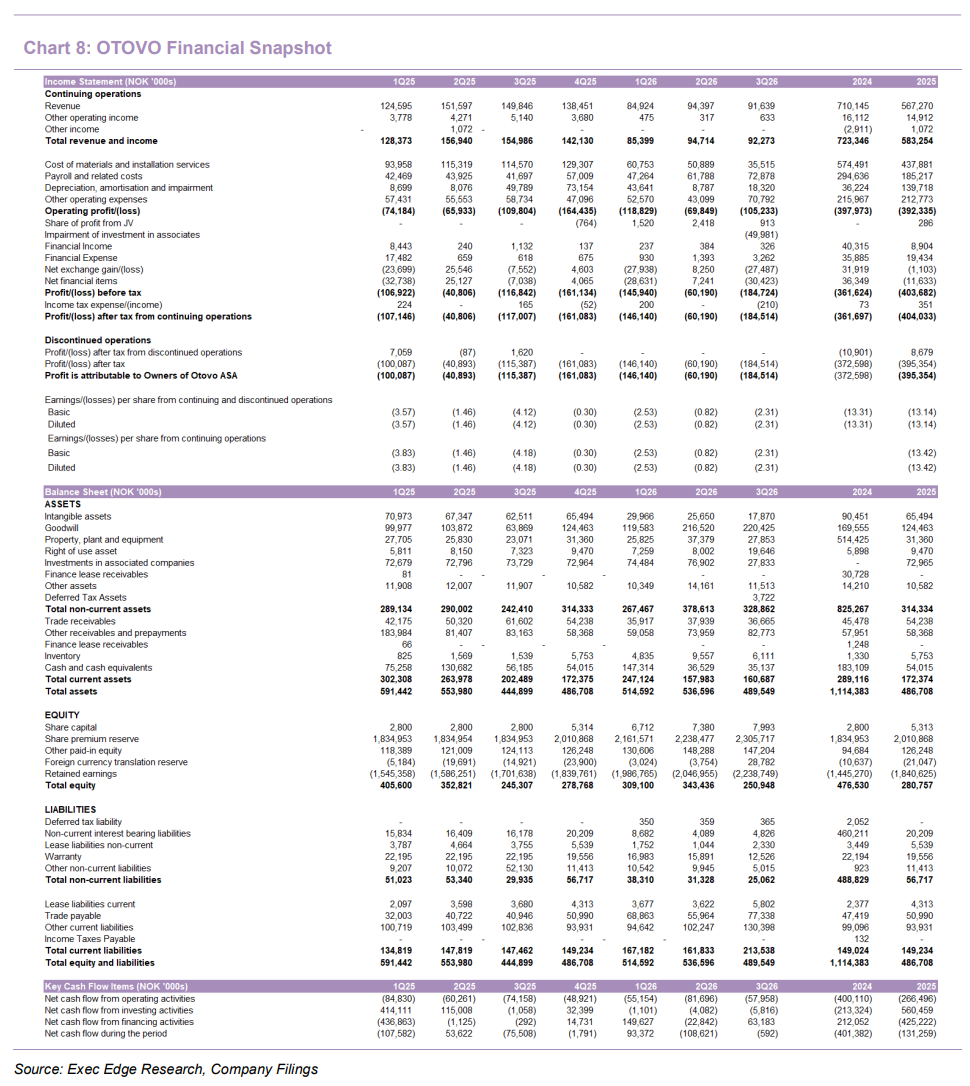
- Monthly adjusted EBITDA turned positive as services-led growth and Endurance efficiencies drove a profitability inflection. OTOVO reported 3Q26 revenue of NOK 91.6 million ($9.7 million), down 39% y/y and 3% q/q, as the planned contraction in European Newbuild continued to offset U.S. services growth. However, the revenue mix improved significantly, with Field and Recurring Services contributing 65% of revenue versus 39% in 2Q26. Gross profit increased 40% y/y to NOK 56.8 million despite lower revenue, while adjusted EBITDA improved $1.2 million sequentially to negative $3.2 million, with OTOVO achieving its first positive monthly adjusted EBITDA in September. This milestone marks tangible progress in OTOVO’s transformation into a profitable, AI-enabled energy services platform, supported by accelerating services growth and a structurally lower cost base.
- Field Services growth accelerated OTOVO’s transition toward a higher-margin, services-led business model. Field Services revenue increased 70% q/q to NOK 53.5 million ($5.6 million) from NOK 31.1 million, driven by organic work-order growth, higher technician utilization and the consolidation of SunSystem Technology (SST). Recurring Services revenue increased to NOK 6.0 million from NOK 5.6 million, supported by Otovo Care memberships and service arrangements. Conversely, Newbuild revenue declined 44% q/q to NOK 32.1 million from NOK 57.7 million, reflecting reduced spending on traditional installation customer acquisition. Combined services revenue increased approximately 62% q/q to NOK 59.5 million, while the U.S. became OTOVO’s largest revenue contributor for the first time. The growing services mix reduces dependence on installation cycles while expanding opportunities for repeat repairs, memberships and equipment upgrades.
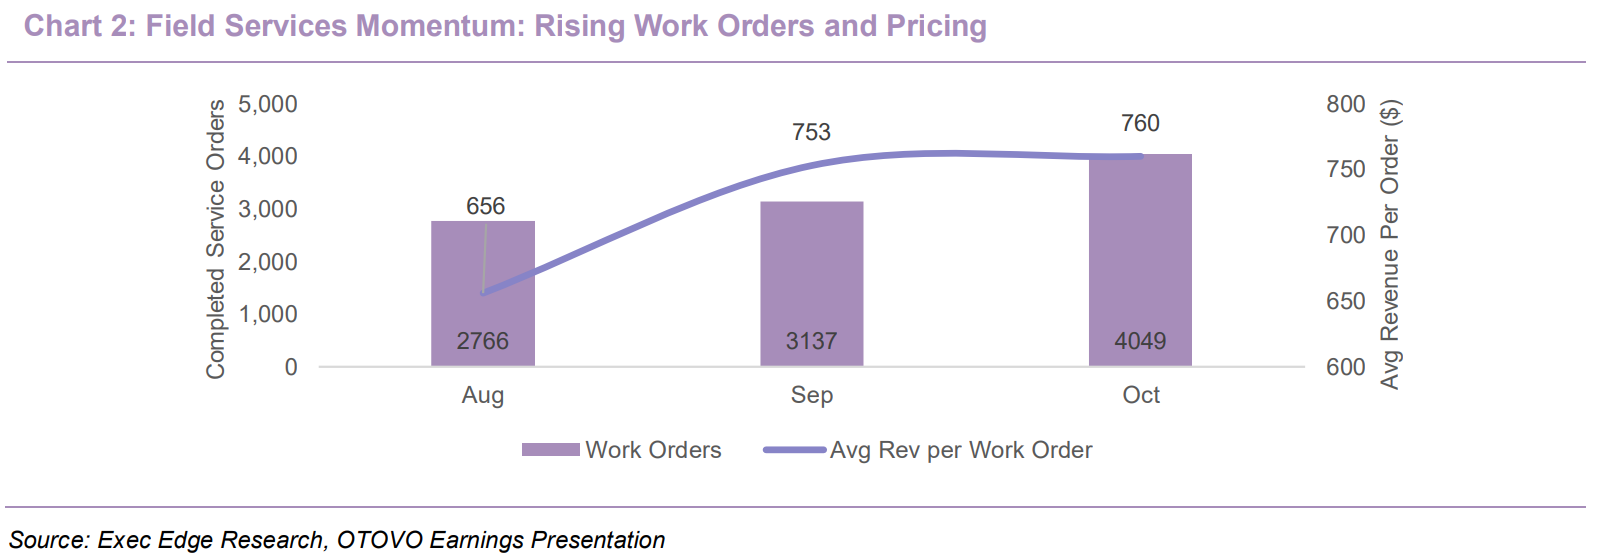
- October work-order momentum accelerated Field Services growth, with higher volumes, pricing and margins reinforcing improving unit economics. Completed service orders reached 4,049 in October, up 29% m/m and 46% from August’s 2,766, while average revenue per order increased to $760 from $656 and estimated gross margin expanded to 52% from 46%. Consequently, estimated monthly Field Services revenue reached $3.1 million, equivalent to approximately 55% of the entire 3Q26 Field Services revenue of $5.6 million. Higher technician utilization and work-order pricing are driving stronger unit economics, while incoming orders continue to exceed completions, providing visibility into further growth as technician capacity expands. At October’s unit economics, management estimates that every additional 1,000 monthly work orders could contribute approximately $4.7 million in annualized EBITDA, assuming no incremental overhead, highlighting the operating leverage potential as service volumes scale.
- Endurance is translating AI-enabled automation into higher technician productivity and structural overhead savings. OTOVO’s proprietary AI platform integrates customer intake, diagnostics, quoting, scheduling, dispatch, procurement and billing, replacing fragmented systems across acquired businesses. More than 70 third-party applications have been eliminated, while automated routing and scheduling have improved daily truck rolls per technician by over 30%, with customer response times targeted within five minutes. OTOVO is also internalizing computing infrastructure, acquiring approximately $20,000 of hardware as an alternative to an estimated $50,000 to $60,000 in equivalent monthly cloud infrastructure costs, highlighting further cost-saving potential. By consolidating technology and operating processes, Endurance enables acquired service teams to scale without proportionate administrative overhead, strengthening operating leverage as service volumes expand.
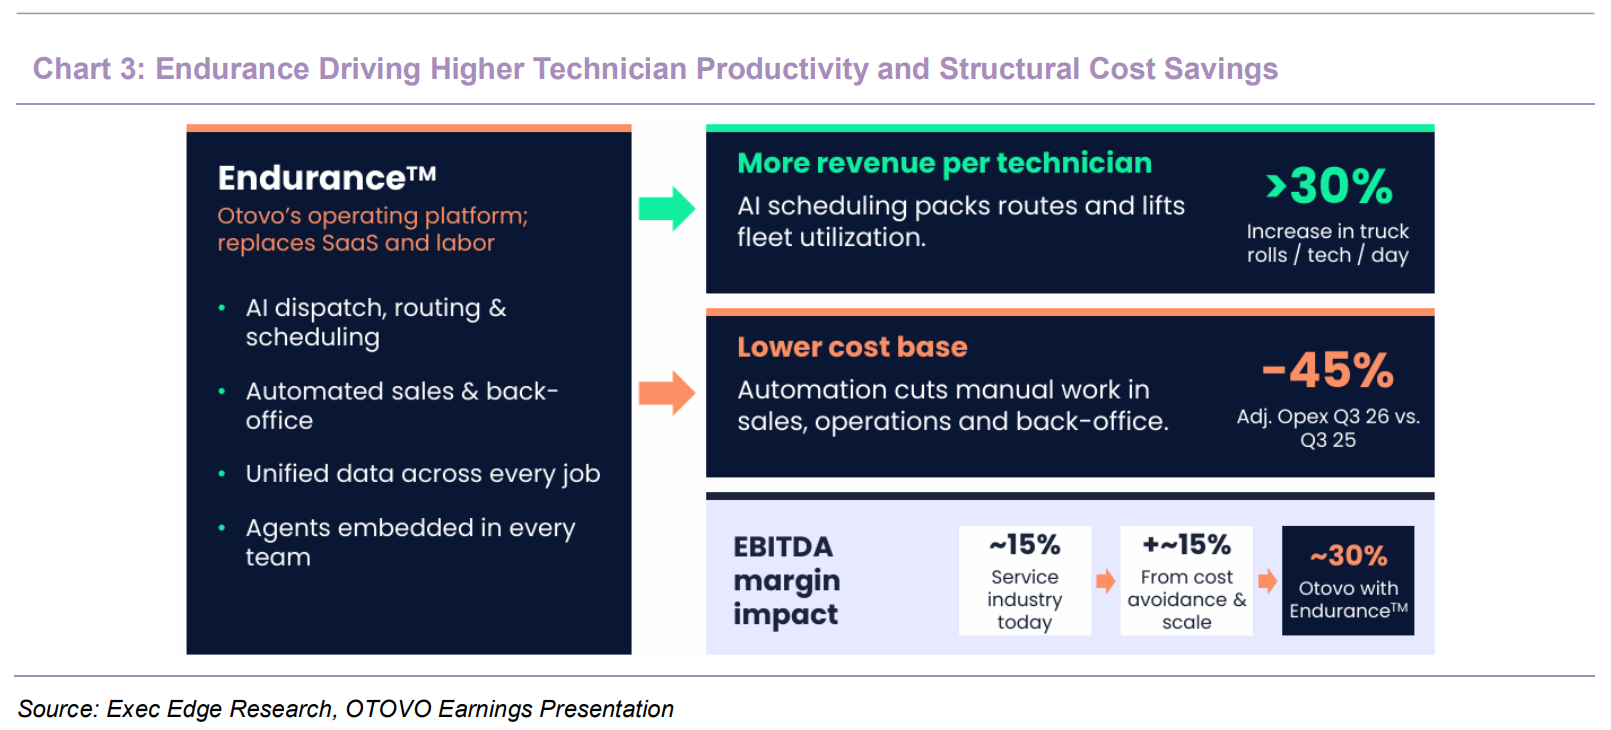
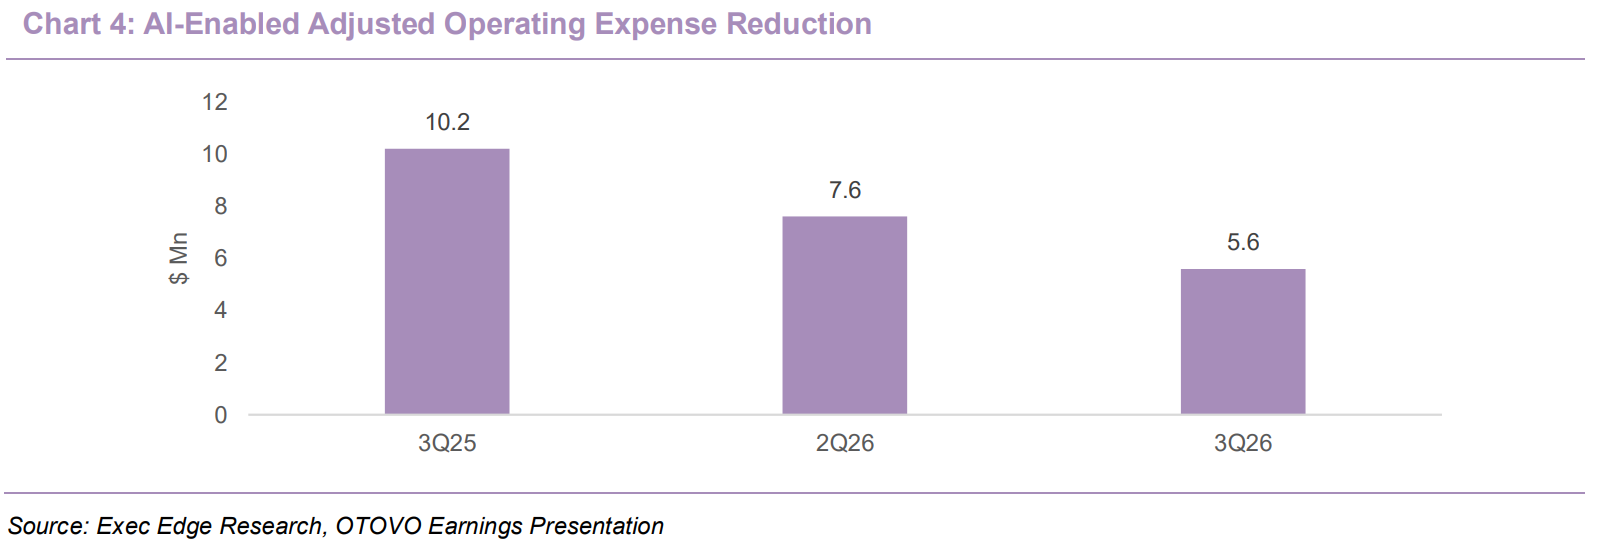
- AI-enabled cost reductions drove improved operating leverage and a narrowing adjusted EBITDA loss. Adjusted operating expenses declined 26% q/q and 45% y/y to $5.6 million in 3Q26, from $7.6 million and $10.2 million, respectively. Organic adjusted expenses fell 20% q/q to $5.2 million, more than offsetting the impact of acquired-business costs, supported by lower marketing expenses, workforce restructuring, office closures and software consolidation. Adjusted EBITDA improved to negative $3.2 million from negative $4.4 million q/q and negative $6.1 million y/y, with the company achieving positive monthly adjusted EBITDA in September. The current adjusted cost base of approximately $1.9 million monthly is already within the 2027 operating framework, with additional SaaS savings expected in 4Q26 as contracts expire. Management expects further cost efficiencies to support continued positive monthly adjusted EBITDA through 4Q26 and beyond, reinforcing the earnings potential of OTOVO’s expanding services platform.
- Services-led growth drove significant gross margin expansion, reinforcing the profitability benefits of OTOVO’s business mix transformation. Gross profit increased 40% y/y to NOK 56.8 million, lifting reported gross margin to 62% from 46% in 2Q26 and 27% in 3Q25. Importantly, reported gross margin excludes internal technician labor, which is recorded under payroll expenses, whereas outsourced Newbuild installation labor was included in cost of sales, affecting comparability across periods. On a management reporting basis, Field Services generated NOK 24.4 million of gross profit at a 45.6% margin, while Newbuild recorded a negative NOK 16.9 million segment result, partly reflecting inventory write-offs and an Italian warranty accrual adjustment.
- Underlying operating improvements are increasingly evident despite one-time and noncash charges weighing on reported profitability. Reported EBITDA was negative $9.1 million versus adjusted EBITDA of negative $3.2 million, reflecting $5.9 million of adjustments, including $2.4 million in U.S. listing expenses, $1.2 million in acquisition and restructuring costs, and $1.7 million in noncash items. Net loss widened to NOK 184.5 million from NOK 115.4 million y/y, including a NOK 50 million EDEA impairment and approximately NOK 27 million in largely noncash FX losses.
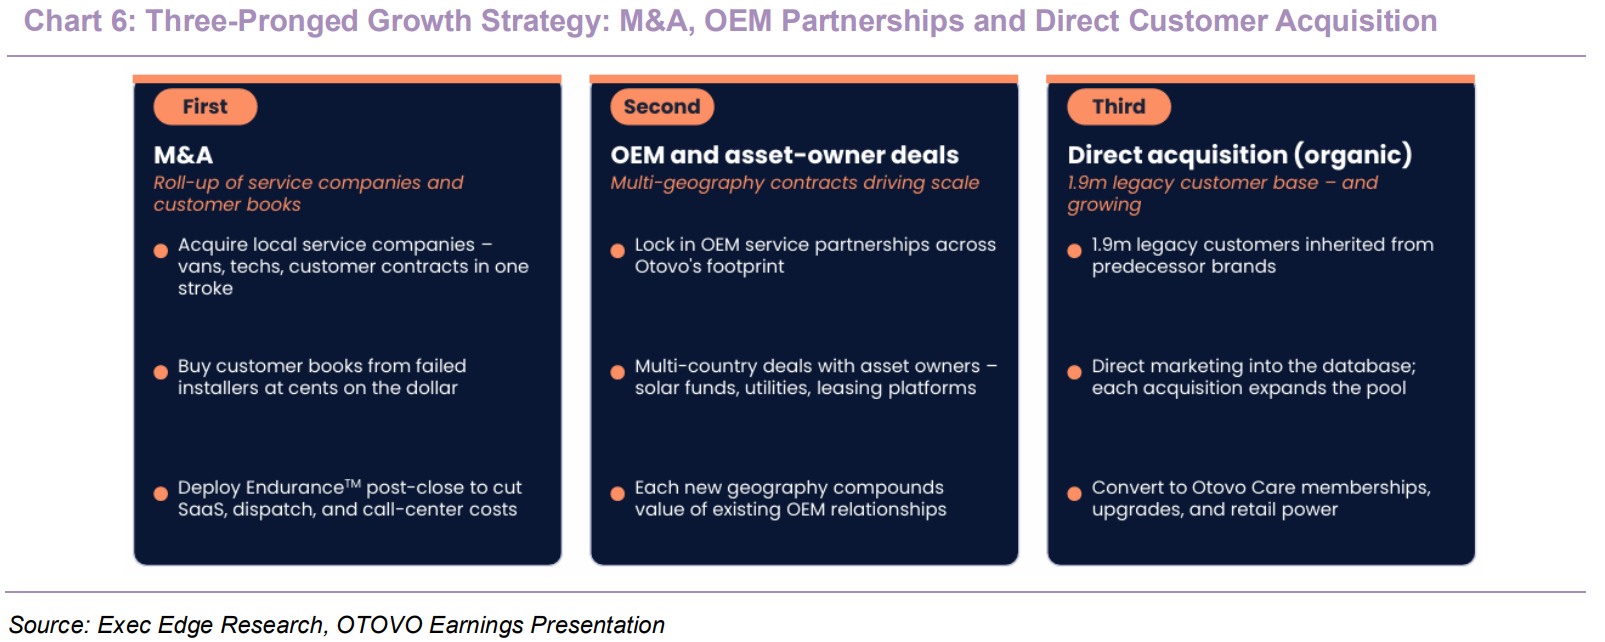
- Strong service-level unit economics and expanding technician capacity underpin OTOVO’s 2027 outlook for approximately 30% adjusted EBITDA margins. Management targets approximately $120 million in revenue and $36 million in adjusted EBITDA (~30% margin), supported by 14,200 monthly Field Services work orders at $700 per order and 50% gross margin. This translates into $9.94 million in monthly service revenue and $2.82 million to $3.22 million in adjusted EBITDA, after monthly adjusted SG&A of $1.75 million to $2.15 million. Importantly, October’s $760 revenue per order and 52% gross margin already exceed management’s 2027 assumptions, providing early validation of the targeted unit economics, with further growth driven primarily by scaling work-order volumes approximately 3.5x from October’s 4,049. Technician capacity increased from just 13 at the start of 2026 to 129 in early November, with approximately 300 targeted by year-end, including roughly 112 technicians anticipated through pending acquisitions. The 2027 framework requires approximately 325 to 375 technicians, with roughly two-thirds of the targeted capacity expected from organically recruited technicians and one-third through acquisitions. Management’s expanding recruitment pipeline and acquisition strategy provide a path toward the required service capacity, supporting its outlook for substantial revenue growth and profitability expansion in 2027.
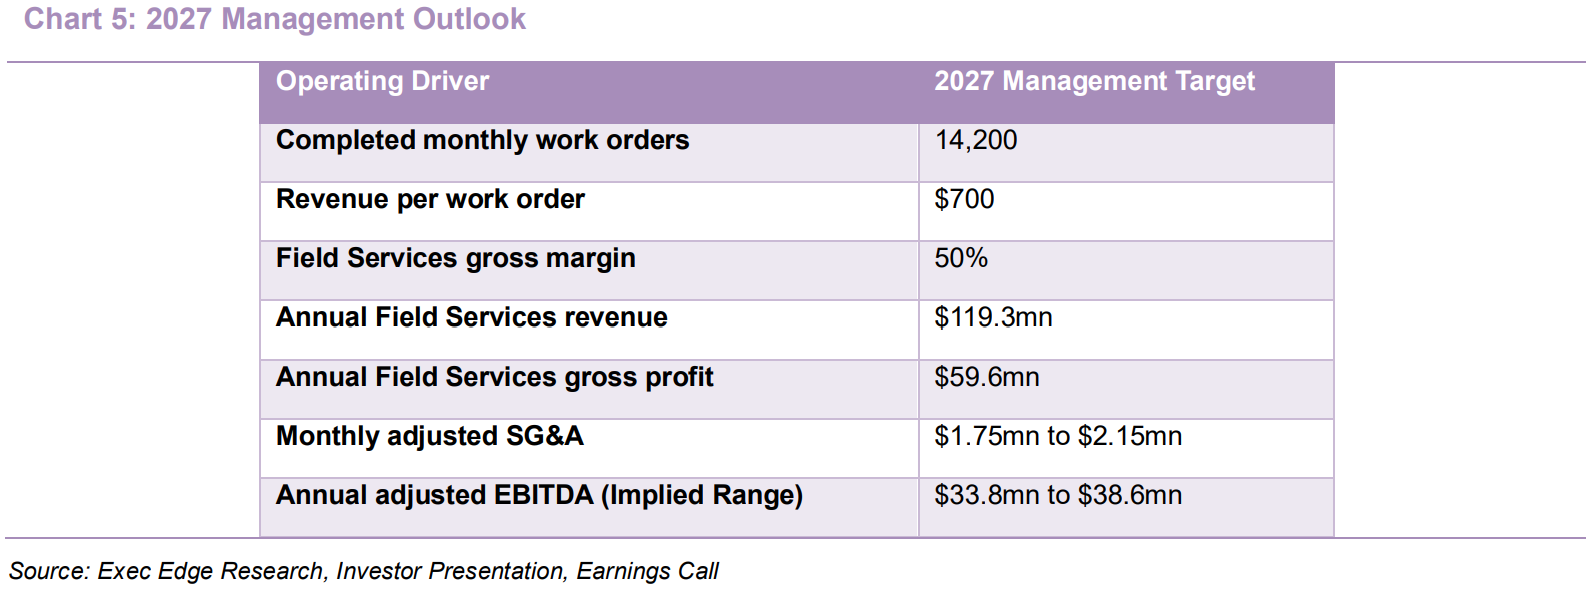
- OTOVO’s three-pronged growth strategy combines acquisition-led expansion, OEM and asset-owner partnerships, and direct customer acquisition to accelerate service volumes and profitability.
- Acquisitions are accelerating OTOVO’s geographic expansion, technician capacity and field-service scale. OTOVO has completed eight acquisitions since December 2025, including SunSystem Technology in July and PV Hawaii in October, with three additional transactions or alternatives targeted by year-end. PV Hawaii expanded the U.S. footprint to 17 states. The $0.7 million initial consideration comprises $0.2 million paid at closing and a $0.5 million promissory note, plus a potential earn-out of up to $0.8 million over three years. Green Panel remains under definitive agreement at approximately $11 million, pending closing. Endurance provides a common operating platform across acquired businesses, supporting higher technician utilization and operating leverage as service volumes scale.
- Endurance integration is central to converting OTOVO’s acquired service network into a profitable operating platform. EnergyAid generated NOK 18.2 million of revenue and a NOK 31.6 million loss from its April acquisition through September, while SST contributed NOK 5.0 million of revenue and a NOK 11.0 million loss since July. EnergyAid was acquired through shares valued at NOK 92.7 million, while SST’s initial consideration was $0.77 million, excluding employment-contingent remuneration. Endurance is expected to improve work-order density, procurement efficiency and administrative costs across these businesses. The appointment of Yaniv Avni as COO strengthens execution capabilities. Avni previously led service operations at SolarEdge, overseeing more than 3 million systems and 10 GW of installed capacity, bringing relevant experience in large-scale field-service operations and OEM relationships.
- OEM and commercial partnerships are expanding OTOVO’s service opportunity across the solar repair and repowering market. OTOVO completed more than 1,000 inverter replacements using Tigo Energy technology, demonstrating early traction in solar repowering. Tigo’s open architecture enables servicing of diverse legacy systems, supporting an opportunity as an estimated 400,000 U.S. residential solar installations annually reach ten years of age over the next five years. Commercial opportunities are also expanding through Freedom Solar, covering warranty-related rights for 417 installations representing approximately 70 MW, and InCharge Energy across solar, storage and EV charging. These relationships expand OTOVO’s addressable service base and support higher work-order volumes, recurring contracts and technician utilization across its growing geographic footprint.
- OTOVO’s shift toward installed-base monetization and recurring services is creating a more cost-efficient customer acquisition model. Marketing expenditure declined 79% y/y to NOK 6.2 million from NOK 29.6 million, reflecting reduced Newbuild acquisition spending and greater focus on existing customer relationships. OTOVO’s customer base exceeded 65,000 in October versus approximately 60,000 in September, alongside previously reported 22,000 memberships and 1.9 million legacy customer records. These represent distinct customer pools with different monetization potential. OTOVO is leveraging this base to drive repairs, equipment upgrades and Otovo Care memberships at lower customer acquisition costs. Recurring Services currently generates approximately $0.7 million in quarterly revenue, with higher membership penetration and retention offering potential to improve revenue visibility and customer lifetime value. Management also intends to selectively reinvest Endurance-enabled cost savings into direct customer acquisition to support organic growth.
- Operating cash burn continued to decline, supported by lower costs and favorable working-capital movements. Operating cash outflow declined to NOK 58.0 million in 3Q26 from NOK 81.7 million q/q and NOK 74.2 million y/y, while 9M26 outflow improved to NOK 198.8 million from NOK 219.2 million. Around NOK 29.0 million of quarterly cash inflow came from working-capital movements, alongside lower operating costs. Trade receivables declined to NOK 36.7 million from NOK 54.2 million at 2025 year-end, while payables increased to NOK 77.3 million from NOK 51.0 million. Inventory remained broadly stable at NOK 6.1 million versus NOK 5.8 million, reflecting limited inventory requirements under the increasingly service-led model. September-end cash stood at NOK 35.1 million versus NOK 36.5 million in June, despite NOK 63.2 million in quarterly financing inflows.
- October equity financing and planned asset disposals strengthened OTOVO’s liquidity position and financial flexibility to support continued expansion. OTOVO raised NOK 28 million in October through 3.5 million new shares at NOK 8 each, increasing shares outstanding to approximately 83.43 million from 79.93 million. Proceeds will support acquisitions, the proposed U.S. dual listing and general corporate purposes. OTOVO also agreed to divest its remaining 4.76% EDEA Europe stake for EUR 2.16 million, alongside its Swiss residential solar portfolio, with closing targeted for December 2026, subject to lender consent and due diligence. The transaction is expected to facilitate repayment of the NOK 15 million revolving credit facility. Management indicated that the recent financing and anticipated asset-sale proceeds are sufficient to fund its current business plan, with the planned debt repayment further strengthening the balance sheet. Continued reductions in operating cash burn and the transition toward positive cash generation would further enhance OTOVO’s ability to fund expansion internally.
Valuation Discount Offers Re-Rating Potential as Services Platform Scales
- Disclaimer: Exec Edge does not publish proprietary estimates, ratings, price targets, or investment recommendations. The valuation discussion below is illustrative only and is based on company filings, management commentary, and third-party data and estimates. It does not constitute a recommendation, price target, rating, or prediction of future pricing.
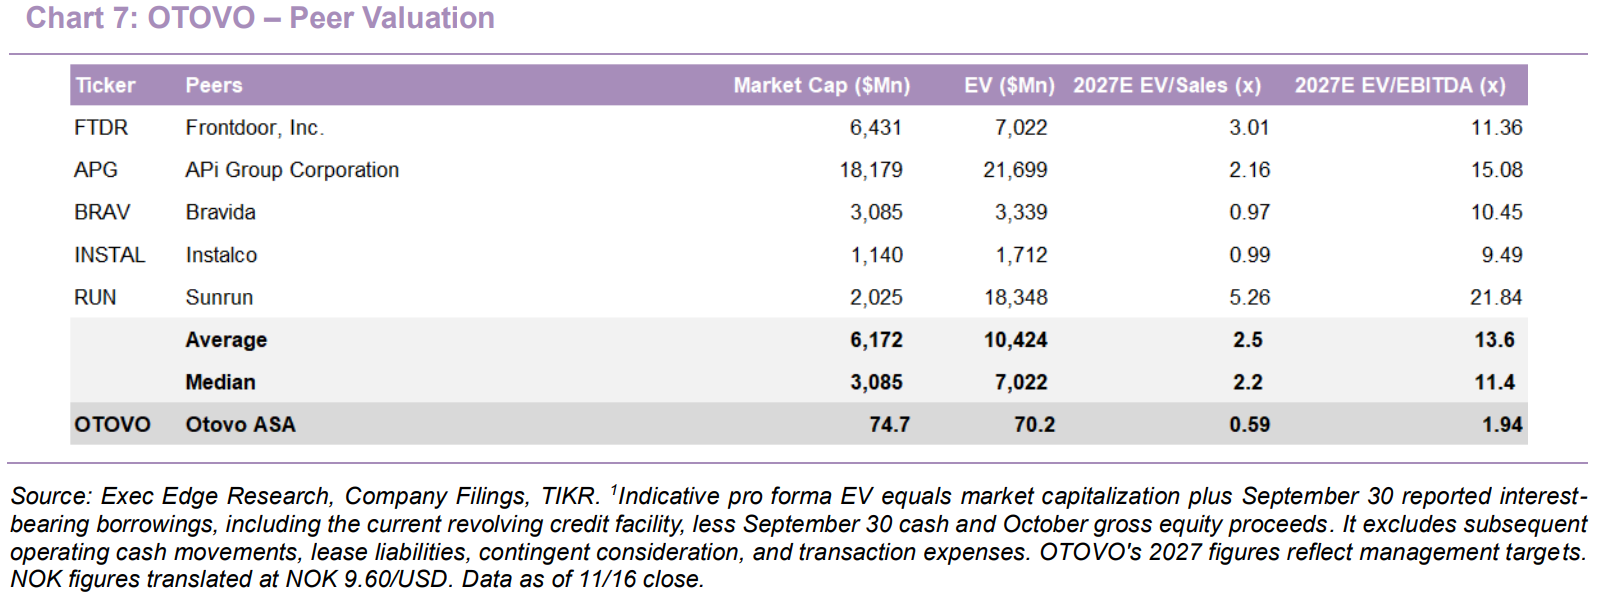
- OTOVO’s discounted valuation offers re-rating potential as the services transformation begins translating into profitability. At NOK 8.60 ($0.90) per share, OTOVO has a market capitalization of NOK 717.5 million ($74.7 million) and an indicative pro forma enterprise value¹ of NOK 674.2 million ($70.2 million), adjusted for the October equity raise. The stock trades at 0.59x EV/2027 targeted revenue of $120 million and approximately 1.94x EV/2027 targeted adjusted EBITDA of $36 million.
- Substantial discount to established service peers highlights meaningful valuation headroom. The peer group trades at average 2027E multiples of 2.5x EV/Sales and 13.6x EV/EBITDA, with medians of 2.2x and 11.4x, respectively. The more comparable service-focused group of Frontdoor, APi Group, Bravida and Instalco averages 1.78x EV/Sales and 11.60x EV/EBITDA. OTOVO’s 0.59x EV/2027 targeted sales represents a roughly 76% discount to the broader peer average and 67% to service-focused peers, reflecting its earlier stage of profitability, acquisition integration requirements and ongoing cash burn. The valuation discount remains substantial despite September’s adjusted EBITDA profitability milestone, accelerating Field Services growth and improving Endurance-enabled operating efficiencies, creating meaningful scope for re-rating as the company delivers on its 2027 earnings targets.
- Scaling service volumes, improving profitability and positive cash conversion could catalyze meaningful multiple expansion. Applying an illustrative 1.10x EV/Sales multiple to management’s $120 million 2027 revenue target implies an enterprise value of approximately NOK 1.27 billion ($132 million) vs. the current EV of NOK 674.2 million ($70.2 million). After adjusting for pro forma net cash, this implies an illustrative equity value of approximately NOK 1.31 billion, or NOK 15.71 per share. This represents an illustrative valuation framework and is not a price target. The 1.10x multiple represents a substantial discount to peers, at approximately 50% below the current broader peer median of 2.2x and 38% below the service-focused peer average of 1.78x. Achieving 14,200 monthly work orders, sustaining approximately 50% Field Services gross margins and converting operating leverage into positive cash flow will be central to narrowing the discount. Endurance efficiencies, successful acquisition integration and reduced dependence on external financing provide additional re-rating catalysts.
Read Exec Edge’s Initiation on Otovo ASA Here
Subscribe to our Weekly Newsletter to Receive All Research
Contact: